Capex peaking

Oracle capex to peak in FY28, or Jun 2027–May 2028.

Following a period of peak capex in FY27-FY28, capital expenditures are expected to step-down in FY29.

– Oracle Investor Day Oct. 28, 2026


MSFT capex missed. Microsoft guided capex for next q is $50bn vs expectation of $53bn, while reported capex for current quarter is $39bn vs expected $46bn.

And MSFT mentioned higher return on capex in future.

we continue to improve the efficiencies of our infrastructure, each dollar of CapEx has the potential to support more revenue and higher returns over time

– Microsoft Fiscal 2027 first quarter earnings call

Sounds to me that capex efficiency is bottoming, which could mean price appreciation in hardware is peaking.


Google stock didn’t do well with higher capex comments in FY2027, although stock is also under pressure with Google ads, which is under threat from AI.

Housing prices after stock market bubble

2000

Buying a U.S. home in 2000 and selling it in 2003 would generally have been very profitable, even as the dot-com bubble collapsed. According to the Case-Shiller U.S. National Home Price Index, home prices increased approximately 28% over those three years, or about 8.5% annualized.

Unlike in the U.S., buying residential property in Tokyo, Singapore or Hong Kong in 2000 and selling in 2003 would generally have lost money.

Chart by ChatGPT

2021

Buying a home in 2021 and selling in 2024 was profitable in the U.S., Tokyo and Singapore, but disastrous in Hong Kong.

Chart by ChatGPT


Some nuances

  • Policy. The Bush administration actively promoted homeownership after the dot-com crash, particularly from 2002 onward
  • Hong Kong and Singapore suffered from SARS in 2003
  • Hong Kong suffered from China geopolitical tension with US/western countries in 2021-24 cycle

Local governments in China investing

1/

The relationship between a company’s management and local political leaders can be a material, underappreciated investment factor in China.

A. Political connections have measurable economic value

Mechanism Benefit of strong relationships Risk when relationships weaken
Bank financing Easier credit coordination and refinancing Tighter credit, higher funding costs
Local infrastructure Faster power, land and construction coordination Delays and additional capex
Government contracts Better access to investment and procurement opportunities Lost orders or weaker contract pipeline
Subsidies More favorable funding allocation Reduced grants and incentives
Problem resolution Faster coordination among multiple agencies Administrative delays
Competition Better access to scarce local resources Competitors gain priority
Financial distress Potential help coordinating restructuring Creditors become less accommodating

B. Leadership turnover could be catalysts.

A study found that local Party secretary turnover increased firm-specific stock crash risk, particularly among private and less transparent companies.

Meanwhile, officials may be promoted, and thus benefit supported companies more; or officials move across country so that companies get into different markets etc.

2/

Forces and relationships between local governments can create interesting phenomenon.

Every city has an incentive to compete for investment, even though they would collectively benefit from less expansion. Even an industry is oversupplied or has low return, a city gets the investment, jobs, tax base and industrial ecosystem.

Other dynamics include local protectionism. A listed company can have superior products and lower costs yet lose procurement contracts because a local government wants to support employers and taxpayers in its jurisdiction. This is particularly relevant to municipal SOE purchasing, government IT, buses, public-sector vehicles and some types of industrial equipment.

Where are China bulls?

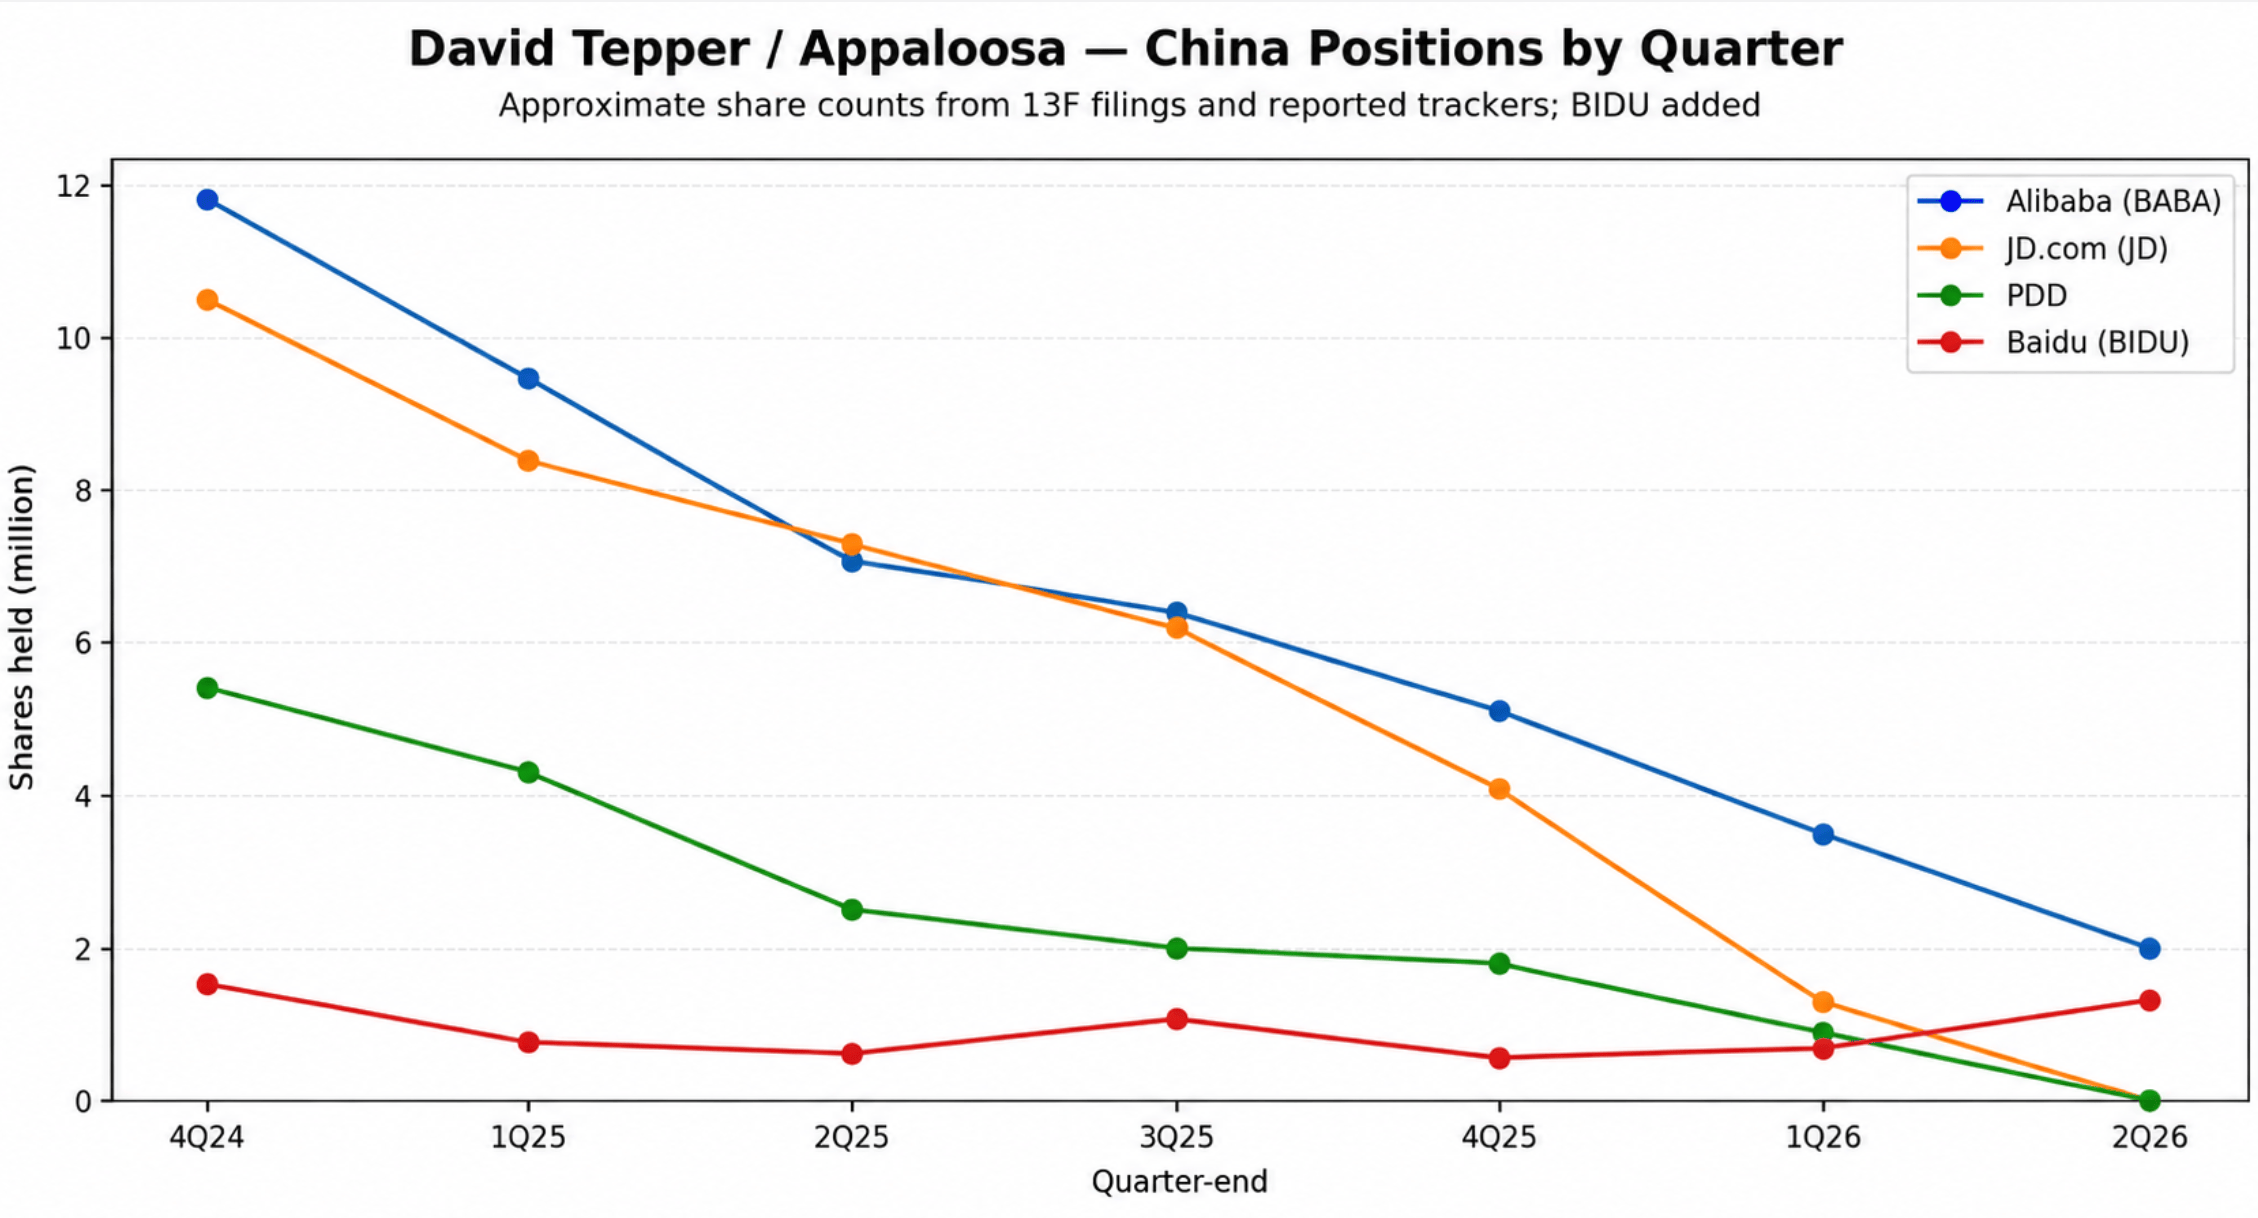
David Tepper was a prominent China bull in 2024.

What happened afterwards? Seem that he has been selling continuously and has mostly exited. His recent add in Baidu is still smaller than his other China sales.


Ray Dalio / Bridgewater similar, even faster exit.

Position 4Q24 shares 1Q25 shares 2Q25 Latest 2Q26
BABA 0.255m 5.660m 0 0
PDD 1.247m 1.743m 0 0
BIDU ~0.197m 2.076m 0 0
JD 0 2.787m 0 0
FXI 1.082m 0.691m 0 0
KWEB no meaningful disclosed position — — —

Source: ChatGPT


Li Lu / Himalaya is more of a long term investor. He recently added PDD and TME.


Interesting levels

Security Apr. 30 close Recent bottom close Bottom vs. Apr. 30 Intraday trough vs. Apr. 30
SK Hynix (000660) ₩1.286m ₩1.322m on Jul. 30 +2.8% −3.1% at ₩1.246m on Jul. 29
QQQ $667.74 $661.73 on Jul. 29 −0.9% −1.0% at $661.14
SOXX $461.44 $465.00 on Jul. 29 +0.8% +0.6% at $464.08
SMH $506.72 $504.22 on Jul. 29 −0.5% −0.6% at $503.63

These names bottomed at end of Apr levels.

From capex to backlog

For the past few quarter, capex figures and related comments from hyperscalers are the key metrics to watch, especially for gauging future demand for semiconductor companies.

The higher the capex number, the higher the revenue estimates.

This worked but became less useful lately.

Investors don’t like it if only the capex is growing, which pushes hyperscalers free cash flows to negative territory.

Investors want to see higher demand signal, which can justify these higher capex numbers.

Thus, backlogs or RPOs (emaining performance obligations) are more important now.


Quarter AWS backlog Microsoft commercial RPO Google Cloud backlog Oracle total RPO
1Q25 189 315 90 130
2Q25 195 368 106 138
3Q25 200 392 155 455
4Q25 244 625 240 523
1Q26 364 627 462 553
2Q26 496 678 514 638

Another thing to watch is the weighted-average backlog duration of these backlogs – within how many years will backlog become revenue?

Microsoft explicitly commented about 2.3 years.

RPO, including OpenAI, has a weighted average duration of 2.3 years. And roughly 30% will be recognized in revenue in the next 12 months, up 37% year-over-year. The remaining portion recognized beyond the next 12 months increased 112%.

– MSFT FY4q26 earnings call

In addition, utilization is also an indicator.

Amazon said “lion’s share” of AWS compute capacity for 2027 had ⁠already been reserved during 2q26 earning call, which is very good to hear.

The World Cup curse

A widely cited study covering World Cups from 1950–2006 found that the U.S. market lost an average 2.58% during the tournament’s defined “effect period,” versus an average gain of 1.21% over comparable-length periods outside World Cups.

The 2022 Crash: During the 2022 Qatar World Cup, the global stock market fell by 4.6% and the S&P 500 dropped by 5.4%.

Why might it happen?

1. Losses hurt more than victories help.
Fans become significantly more pessimistic after elimination, but investors do not become equivalently optimistic after an ordinary victory. During the knockout stage, every match creates one disappointed country, so the negative mood effects may accumulate globally.

2. Investors are distracted.
When a national team is playing, investors watch football instead of markets. Research covering 15 countries during the 2010 and 2014 World Cups found that trading volume could fall by as much as 48% during national-team matches. Domestic markets also temporarily reacted less to global-market news.

The current 2026 World Cup looks fine so far, although Nasdaq is weak in recent days.

The weakness started when US restarted strike on Iran over the Jul 11-12 weekend, after US team’s exit on Jul 6 (defeated by Belgium).


Index June 10 July 17 World Cup return
S&P 500 7,266.99 7,457.69 +2.62%
Dow Jones 49,918.78 52,146.42 +4.46%
Nasdaq Composite 25,169.50 25,520.24 +1.39%
Russell 2000 2,835.46 2,962.22 +4.47%


China’s Jim Cramer?

This Weibo guy, called Feng Ge (Brother Feng), said on July 8 that he can’t withstand the loss and cut positions (in tech mainly).

The next day July 9 stock market came back strong.

On the very strong July 9, he said he bought back (fully invested).

Then on Jul 10 stock market was in a bloodbath.

After Jul 10 close, he said he wouldn’t quit this time – tech is the future and will rise again.

On July 15, he commented that innovative drugs is interesting, which marked the end of a few weeks rally of HK biotech/healthcare stock.

On Jul 16, he commented that “tech has bottomed” / “correction is done”, which is actually the peak of the day.


China’s retail investors have found their Jim Cramer.


Opportunity cost vs sunken cost

Interesting that retail investors care much more about sunken cost than opportunity cost.

For one thing, sunken cost can be easily measured – how much you bought and how much is the unrealized p/l.

Opportunity cost is harder to measure, as you need to constantly have a view on various things.

Perhaps money market fund rate is the most obvious opportunity cost rather than S&P 500, although I believe the latter is more important.

However easiness to measure shouldn’t matter.

As I think sunken cost can be ignored while opportunity cost should be the only thing that matters.

Except that you think you are playing poker with multi round game theory – easy to fold makes you more likely to be bluffed in future.