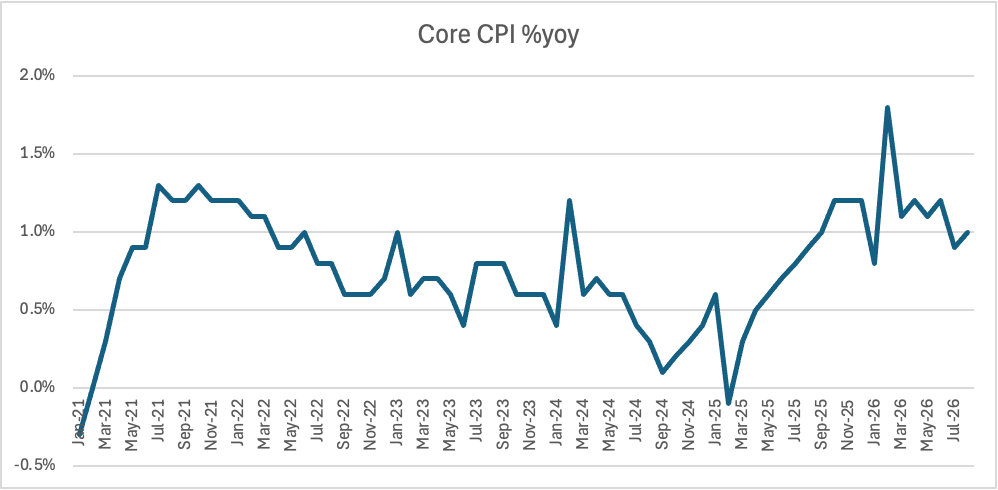
China core CPI has been running near 1% for more than 12 month

China Aug core CPI stood at 1% yoy, the 13th month of running near 1% since Aug 2025.

What were the drivers and policies?

From late 2025 to first half of 2025, trade-in subsidies boost final demand.

Anti-revolution was a focus. On July 1, 2025, Xi chaired the Central Financial and Economic Affairs Commission meeting. It explicitly called for governing disorderly low-price competition and facilitating an orderly exit of outdated capacity. Plus, the July 30 Politburo meeting went further calling to deal with disorderly competition and conduct capacity governance in key industries.

But in the second half of 2025, there was still contribution from previous metals (Jul 2025: gold and platinum jewelry contributed ~0.22ppt to headline CPI), which should be more of a one-off boost.

From Sep 2025 to 2026, China started and expanded government interest subsidy.

Interest and mortgage rates after housing crisis in Japan, US, HK


Property bust Policy/short rate response Mortgage rate
US 2006–09 Fed funds cut to 0–0.25% Dec. 2008 No major reduction during crisis, but later declined to 3–4%
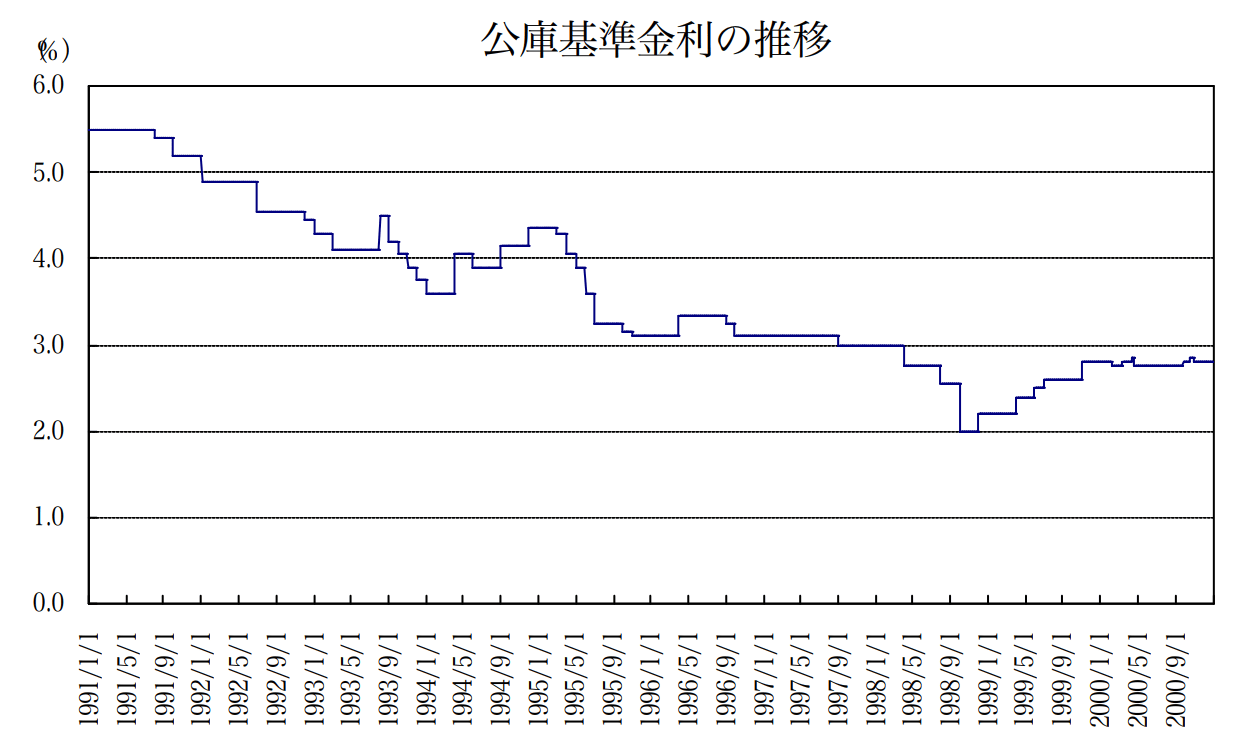
Japan 1990s BOJ adopted near zero policy rate in Feb. 1999 Government housing loans reached 2% in late 1998
Hong Kong 1997–2003 Initially rates went UP, not down, because of HKD peg pressure; reached Different subsidized schemes; can be 0% up to certain point for first home buyers


Japan

Japan’s property bubble peaked around 1990–91, but the BOJ took a long time to reach zero.

In the four years between 1991 and 1995, the official discount rate was cut from 6 percent to 0.5 percent. Before 1994 financial-market deregulation, the discount rate was the principal policy instrument. Deposit and lending rates were administratively linked to it.

On February 12, 1999, the BOJ changed its operating guideline to push the uncollateralized overnight call rate “as low as possible.” It said it would initially aim for around 0.15%, then induce a further decline.

By May 1999, the actual overnight call rate was about 0.03%, which the BOJ itself described as “virtually zero percent” after taking brokerage fees into account.

Meanwhile, the mortgage rate was cut continuously to 2% in last 1998 and kept under 3% for a long time.


US

US housing peaked around mid 2006 (Case-Shiller National Index peaked in July 2006). Total housing starts peaked earlier in January 2006 at 2.273 million, and February 2006 was the first down month at 2.119 million. The financial system is still functioning normally; Fed funds remains 5.25%.

On April 2, 2007, New Century files bankruptcy – subprime origination itself is breaking. Soon afterward, mortgage securities suffer widespread downgrades and nonprime mortgage funding dries up.

During June–July 2007, Bear Stearns hedge funds collapsed. Mortgage losses are visibly migrating from homeowners/lenders into structured-credit investors.

On September 18, 2007, Fed starts cutting rates by 50bps, from 5.25% to 4.75%.

Fed also did 50 bps cut in Dec 2007, 75 bps emergence cut in Jan 2008, another 50 bps before end of Jan 2008, 75 bps cut in Mar 2008 (as Bear Stearns itself went into trouble and merged into JP Morgan), 25 bps cut in Apr 2008. At that point, Fed fund rate target became 2%.

On December 16, 2008, Fed reached Fed reaches effective ZLB by targeting 0-0.25%.

It took 2.5 years from the peak of housing price.

On the mortgage rate side, in 2008 during the acute Lehman/AIG crisis, mortgage rates were still roughly 6–6.5%.

However, that collapsed to 3.3% in 2012.


HK

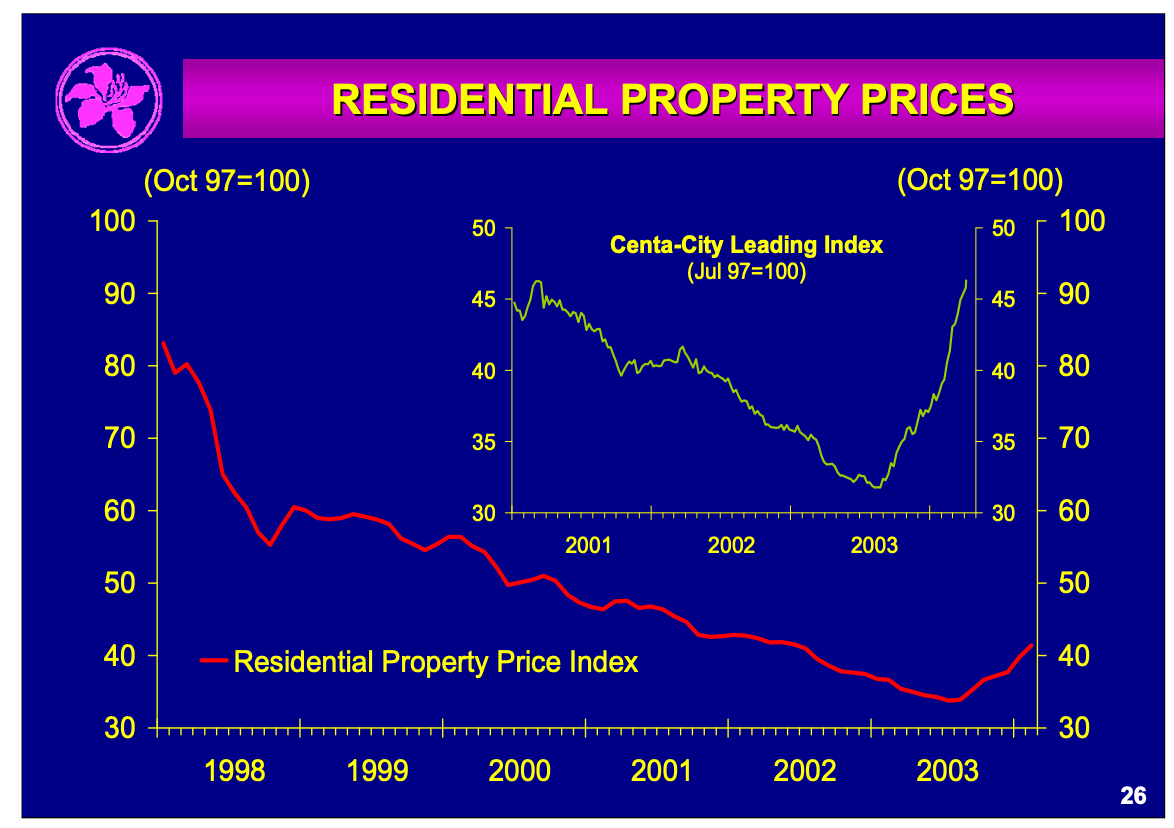
From October 1997 to July 2003, property prices fell by 66%.

Source: link


Event Date Property price
Bubble peak Oct. 1997 R&VD residential index = 172.9 (1999=100)
Asian crisis / HKD attack Oct. 1997 Rates spike; property selloff begins
1998 Very sharp first leg down
1999–2002 Continued deflation / recessionary adjustment
SARS Mar–Jun 2003 Final leg of weakness
Bottom July 2003 ~66% below Oct-1997 peak
Recovery begins H2 2003 Prices rebound rapidly

Hong Kong was a different story as it’s interest rate is not independent, so it doesn’t have as much flexibility to cut rates.

But HK did have other programs to support homebuyers to essentially subsidize mortgages.

Scheme Started Who it targeted Form of subsidy
Home Purchase Loan Scheme (HPLS) 1988, expanded sharply in 1998 PRH tenants / lower-middle-income households 0% interest government loan, or non-repayable monthly mortgage subsidy
Home Starter Loan Scheme (HSLS) Apr 1998 First-time middle/lower-income buyers Low-interest government down-payment loan, up to HK$600k / 30% of property
Mortgage Subsidy Scheme (MSS) Sep 1998 Certain redevelopment/clearance households buying HOS/PSPS Mortgage subsidy up to HK$162k over 6 years
Buy or Rent Option (BRO) Jul 1999 Eligible PRH applicants choosing ownership instead Mortgage subsidy up to HK$162k over 6 years
Home Assistance Loan Scheme (HALS) Jan 2003 Replacement/consolidation scheme 0% loan or monthly mortgage subsidy


The Home Purchase Loan Scheme existed before the crash, from 1988, but Hong Kong massively expanded it in 1998.

It offered an interest-free government loan alongside the bank mortgage. Before the crisis:

  • private-housing / White Form families: HK$400k at 0%
  • public-housing / Green Form tenants: HK$600k at 0%
  • repayment could extend up to 20 years

Alternatively, borrowers could choose a non-repayable monthly subsidy instead of the loan.


Then in July 1998, after property prices had collapsed, the Housing Authority increased the annual quota from 4,500 to 10,000 and added larger/flexible loan options.

By 1999–2000 the enhanced options were:

  • Green Form: HK$800k at 0% over 13 years, or HK$600k over 20 years
  • White Form: HK$500k at 0% over 14 years, or HK$400k over 20 years

Alternatively:

  • Green Form: HK$5,100/month for 4 years
  • White Form: HK$3,400/month for 4 years

and those monthly subsidies did not have to be repaid.

Where are China bulls?

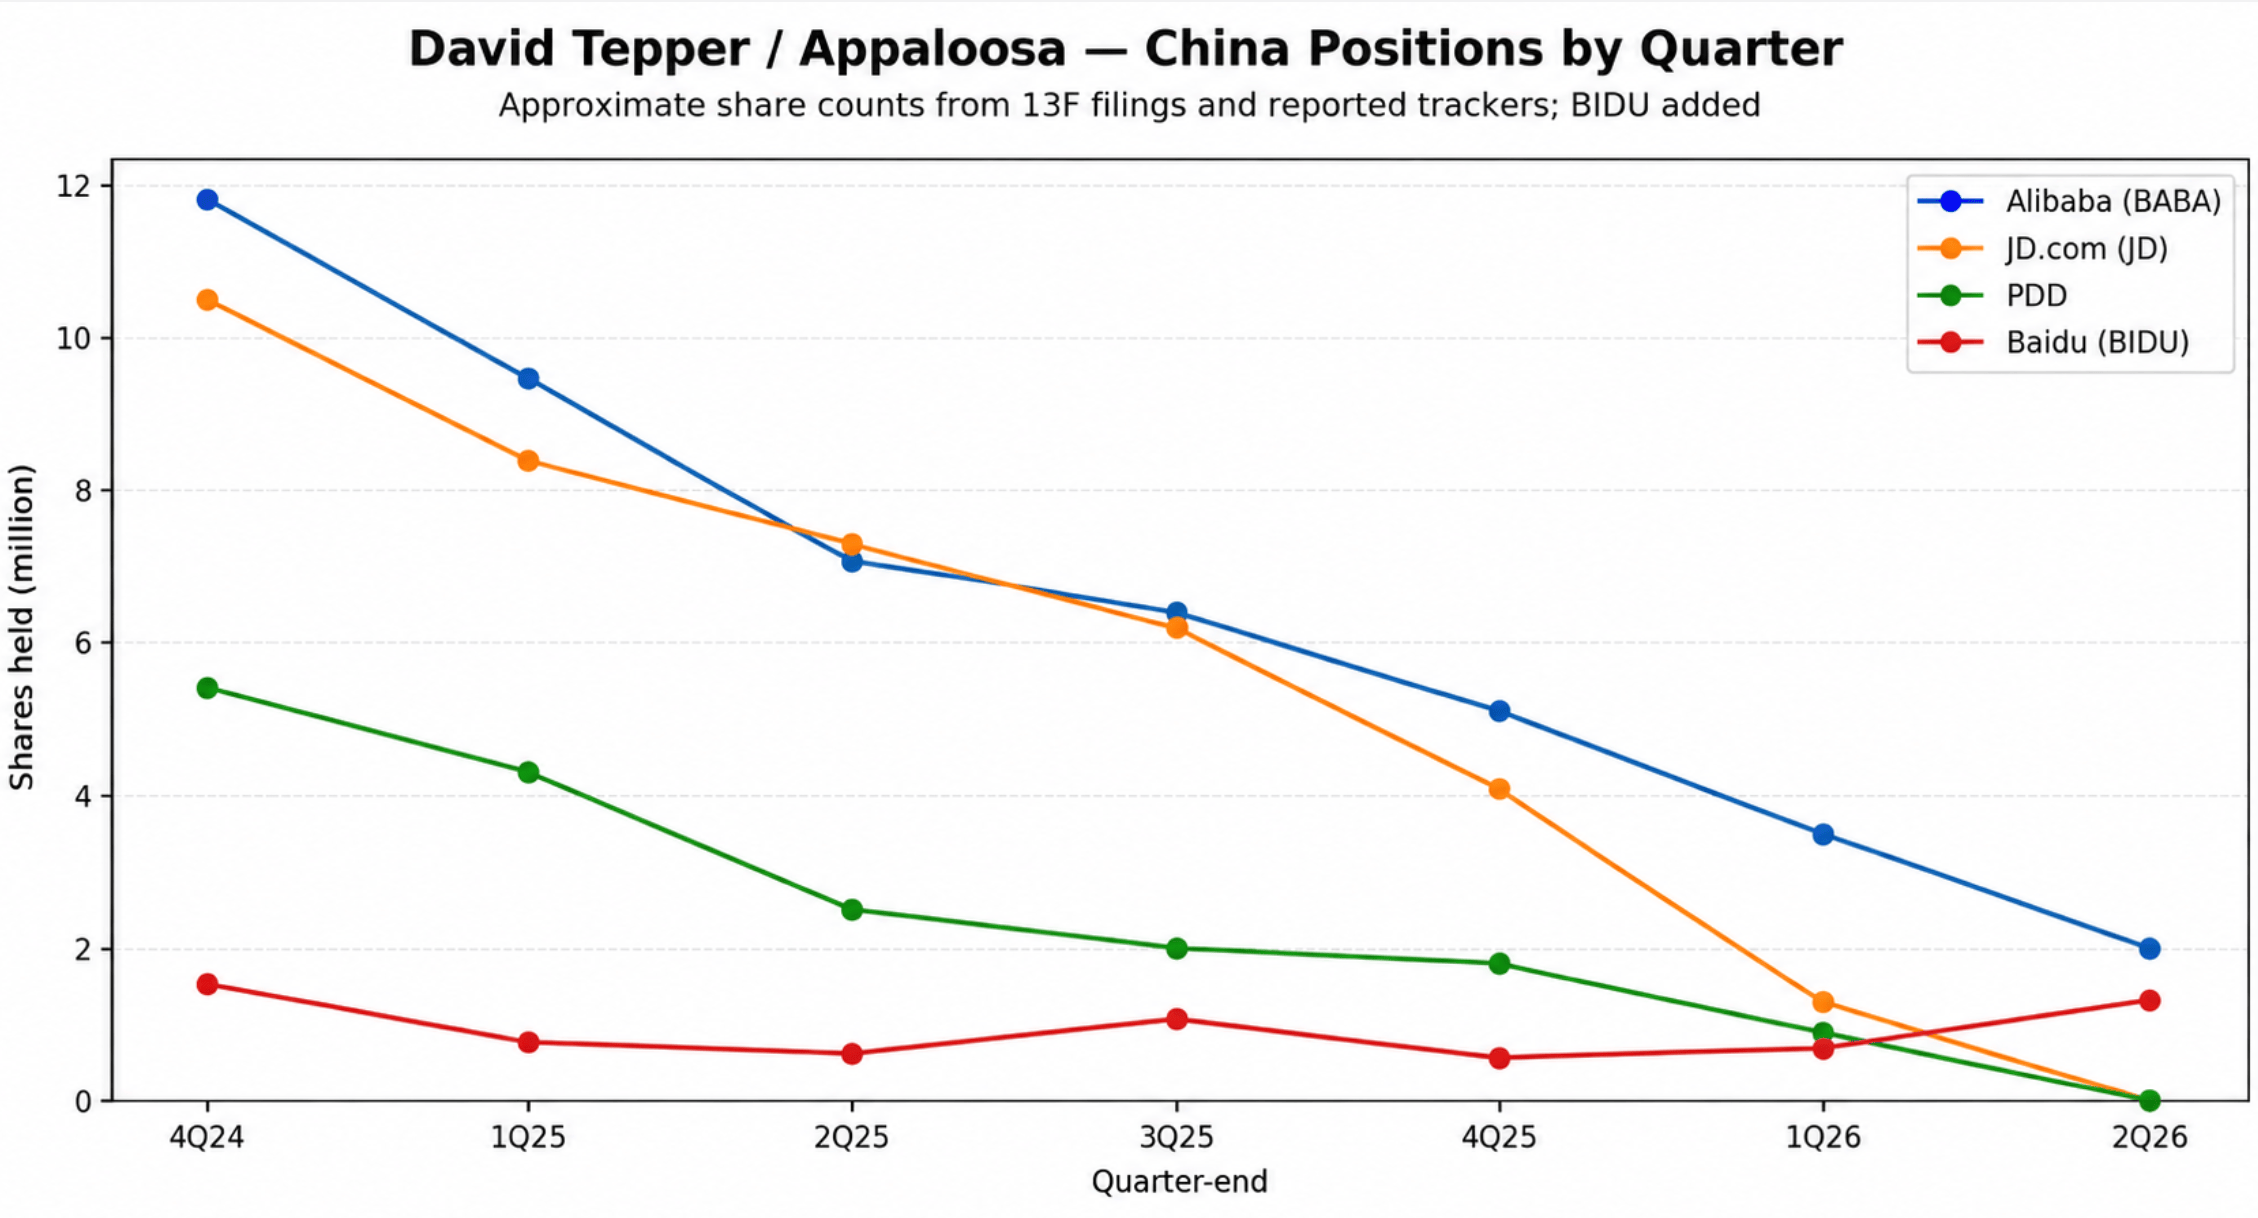
David Tepper was a prominent China bull in 2024.

What happened afterwards? Seem that he has been selling continuously and has mostly exited. His recent add in Baidu is still smaller than his other China sales.


Ray Dalio / Bridgewater similar, even faster exit.

Position 4Q24 shares 1Q25 shares 2Q25 Latest 2Q26
BABA 0.255m 5.660m 0 0
PDD 1.247m 1.743m 0 0
BIDU ~0.197m 2.076m 0 0
JD 0 2.787m 0 0
FXI 1.082m 0.691m 0 0
KWEB no meaningful disclosed position

Source: ChatGPT


Li Lu / Himalaya is more of a long term investor. He recently added PDD and TME.


E-commerce vs express profit pool in US and China

US

2024 2025 YoY
Amazon North America OP $25.0bn $29.6bn +19%
eBay + Etsy OP ~$2.0bn ~$2.2bn +10%
Other e-commerce (Wayfair/Chewy etc.) ~$0.5bn ~$0.5bn ~flat
E-commerce total OP ~$27.5bn ~$32.3bn +17%
UPS U.S. Domestic Package OP ~$4.4bn ~$3.9bn -10%
FedEx domestic/express proxy OP ~$4.8bn ~$4.9bn ~flat
Delivery total OP ~$9.2bn ~$8.8bn -4%
E-commerce / Delivery ~3.0x ~3.7x

China is like 10x.

PDD + BABA + JD retail already 350bn rmb profit.

And express side is 35bn, combining ZTO, YTO, STO, SF, Yunda, JT China.


China E-commerce were more profitable relatively to delivery.

An interesting perspective on China’s investment and consumption from Shan Weijian

The full interview is here.

Shan’s overarching thesis is that China’s consumption potential hasn’t been fully released.

He argued that China’s property problem was a drag, but housing price looks stabling, citing 2026 Jan to May Shanghai housing price up.

Further, he argued that nation wide housing rental yield is 2.8% and is meaningfully higher than China’ sovereign debt yield, which makes housing interesting as an asset class.

The argument on cost of construction has some merit, but that includes cost of land.

The part of 买涨不买跌 and 卖跌不卖涨 is a bit confusing to me as this is more short-term psychology influencing supply demand but not fundamentals.

I have a different opinion.

I think to housing has stabilized is probably pre-mature.

Some positive drivers can be short-lived, such as

– a good A-share stock market in 1H2026 (CSI300 17.66% in 2025 and 7.55% in 1H26, STAR50 60.86% in 2025 and 64.25 in 1H26)

the large number of IPOs in HK and A-share,

– policy driven demand – such as “Shanghai seven measures” in Feb 2026; Shanghai gov recently introduced new measures to support housing market.

—-

Assume housing stabilization is true, which definitely has positive impact on consumption, it doesn’t necessarily mean consumption will be up.

There are many other factors, including confidence in the job market and income level, savings for retirement and healthcare, culture etc.

—-

However, I do sense that Chinese gov is doing more to stabilize housing price and consumption, although policy is not at a stimulating level.

And I do agree Chinese gov has more capacity / more policy in the toolbox.

中国地方政府为什么更喜欢“造东西”,而不是“让人消费”?// Why Do Chinese Local Governments Prefer Building Things Over Boosting Consumption?

一个很重要、但经常被忽略的原因,是税制激励。

中国现行增值税是中央和地方共享税。2016年营改增后,地方分享比例从25%提高到50%,而地方拿到的这部分收入,仍然很大程度上跟企业纳税地绑定。换句话说,一家汽车厂、电池厂、化工厂落在哪里,哪里不仅拿GDP、就业和投资,也能拿到持续的增值税税源。

这会自然强化地方政府的制造业偏好。

假设一个新工厂每年创造10亿元应缴增值税。过去地方可能只分到2.5亿元,2016年以后可以分到5亿元。再叠加企业所得税、城建税及各种附加,一个大型制造项目对地方财政的价值非常高。

于是地方政府最合理的行为,就是抢工厂、抢产能、抢总部、给土地、给融资、建产业园。单个地方这样做完全理性,但全国所有地方一起这样做,就容易形成重复投资和过剩产能。

反过来,一个居民多消费1000元,对当地政府的财政收益却没有那么直接。

比如上海居民买一辆安徽生产的车,制造企业缴纳的增值税税源主要仍跟企业纳税地相关。上海创造了最终需求,却未必能像生产地一样直接获得对应税收。

这就是中国税制一个很重要的结构性特征:

地方财政更奖励“生产发生在哪里”,而不是“消费发生在哪里”。

其实“消费地”并不一定难定义。实体商品可以按最终收货地,线下消费可以按门店所在地,汽车可以按上牌地;数字订阅没有收货地址,也可以按信用卡或支付账户的账单/KYC地址归属。规则不需要做到哲学意义上的100%准确,只要统一、稳定、可验证即可。

因此,中国并不一定需要简单加税。可以降低一部分现有VAT,同时把对应税率改成按最终消费地归属的sales tax;或者更简单,把现有地方VAT的一部分从“纳税地分配”改成“消费地分配”。

核心不是税叫什么名字,而是地方政府面对什么激励。

如果新增一座工厂能明显增加地方财政收入,而新增100亿元居民消费却不能,那么地方政府自然会继续优先招商、投资和扩产。

所以中国“重投资、重制造、轻消费”不仅是产业政策问题,也有很强的财政制度基础。

想真正刺激消费,除了给居民发钱,更重要的是让地方政府也能从消费增长中赚钱。


One important but often overlooked reason is the incentive created by China’s tax system.

China’s VAT is shared between the central and local governments. After the 2016 VAT reform, the local share rose from 25% to 50%. Crucially, much of that local revenue is still tied to where the company pays tax. So when an auto plant, battery factory, or chemical plant locates in a city, the local government gets not only GDP, jobs, and investment, but also a recurring VAT tax base.

That naturally strengthens the incentive to attract manufacturing.

If a new factory generates RMB1 billion of VAT a year, the local government might have received roughly RMB250 million before 2016 and RMB500 million afterward. Add corporate income tax, urban maintenance tax, and other surcharges, and a large manufacturing project becomes extremely valuable to local finances.

The rational response is obvious: compete for factories, capacity, headquarters, industrial parks, land investment, and financing support. That may be rational for each individual locality, but when every locality behaves the same way, the national result can be duplicated investment and excess capacity.

Consumption works differently.

If a Shanghai resident buys a car produced in Anhui, much of the VAT-related local revenue still follows the producer’s tax location. Shanghai creates the final demand, but it does not necessarily capture the corresponding marginal tax revenue in the same way Anhui does.

This creates a structural bias:

Local fiscal systems reward where production happens more than where consumption happens.

A consumption-based system does not necessarily have to be technically complicated. Physical goods could be sourced based on the final delivery address, offline services based on the store location, and cars based on the registration location. For digital subscriptions with no shipping address, the tax could be assigned using the billing or KYC address of the credit card or payment account.

The rule does not need to identify the philosophically perfect “true” place of consumption. It only needs to be uniform, stable, and verifiable.

China therefore would not necessarily need to raise taxes. One option would be to reduce part of the existing VAT and replace it with a sales tax allocated according to the final place of consumption. An even simpler option would be to keep the VAT system intact but redistribute part of the local VAT share based on consumption rather than the producer’s tax location.

The key question is not what the tax is called. It is what behavior the fiscal system rewards.

If building another factory clearly increases local government revenue, while another RMB10 billion of household consumption does not, local governments will naturally continue to prioritize investment, manufacturing, and capacity expansion.

China’s bias toward investment and manufacturing is therefore not only an industrial-policy issue. It is also embedded in the fiscal system.

If China wants to stimulate consumption structurally, it is not enough to give consumers more money. Local governments also need to make more money when consumption rises.
HK record financing

Alibaba now tops the list with 80bn HKD financing.

排名 公司 / 时间 规模 关键 Terms HKEX 官方公告
1 阿里巴巴 9988 8/23交易,8/24公告 HK$80.0bn 710m新股;HK$112.70;较参考股价折价约3.6%;扩大后占股本3.57%;net约HK$79.7bn;预计8/26交割 HKEX 配售条款公告
2 中际旭创 3308 7/30上市 HK$53.410bn IPO 54.5m股 × HK$980;net HK$52.891bn;另有8.175m股绿鞋,但该HK$53.41bn数字未计绿鞋 HKEX 最终发售价及配发结果
3 宁德时代 3750 4/28 HK$39.190bn 配售 62.385m H股 × HK$628.20;较前收折价7.0%,较5日均价折价10.46%;扩大后稀释约1.36%。 HKEX 配售条款公告
4 智谱 2513 7/9 HK$31.411bn 最多 19.78m H股 × HK$1,588;较前收折价12.99%,较5日均价折价6.72%;扩大后约4.25%。 HKEX 配售条款公告
5 立讯精密 2475 7/9上市;8/5绿鞋 ≈HK$25.060bn 基础 383.473m股 × HK$63.28 = HK$24.266bn;8/5部分绿鞋 12.542m股 × HK$63.28 ≈ HK$0.794bn IPO最终结果 · 绿鞋公告
6 胜宏科技 2476 4/21上市;4/22绿鞋 ≈HK$23.135bn IPO最终95.85m股、HK$209.88,基础gross HK$20.117bn;随后全额绿鞋14.3775m股,同价发行。(HKEX News) IPO最终结果 · 全额绿鞋公告
7 美的集团 0300 5/6定价;5/7公告 HK$17.248bn 两档各HK$8.624bn、均zero coupon、100%发行。2027档:到期11 May 2027、转股价HK$96.82;2033档:到期13 May 2033、转股价HK$115.76,到期赎回114.95%。 HKEX 双档CB完整条款
8 MiniMax 0100 7/10 HK$16.041bn 配售:35.6m股 × HK$268 = HK$9.541bn;另发 HK$6.5bn zero-coupon CB,100%发行,约7/14/27到期,初始转股价HK$335,较前收premium 12.64%,到期赎回102.75%。 HKEX 配售+CB完整条款
9 联想集团 0992 6/17交易;6/18公告 US$2.0bn zero coupon、100%发行、7年期,到期25 Jun 2033;初始转股价HK$36.70,较签约日收盘价premium约47.5%;net约US$1.979bn。 HKEX CB完整条款
10 MMG 1208 6/16 HK$6.268bn + US$0.8bn CB 配股 705.892m股 × HK$8.88;另发US$800m zero-coupon CB,发行价102%,所以CB gross cash为US$816m;21 Jun 2027到期;初始转股价HK$10.21 HKEX 配售+CB完整条款
11 牧原股份 2714 2/6上市;3/5绿鞋 ≈HK$12.099bn 基础 273.9514m股 × HK$39 = HK$10.684bn;3/5部分绿鞋 36.2717m股 × HK$39 ≈ HK$1.415bn IPO最终结果 · 绿鞋公告
12 紫金矿业 2899 1/29交易;1/30公告 US$1.5bn face / US$1.5375bn gross zero coupon;发行价102.5%;5 Feb 2031到期;初始转股价HK$63.30,较前收premium 37.19%、5日均价premium 45.92%。(HKEX News) HKEX CB完整条款
13 中国宏桥 1378 4/28 RMB10.2bn USD-settled zero coupon CB;100%发行;3 May 2027到期;初始转股价HK$43.90 HKEX CB完整条款
14 东鹏饮料 9980 2/3上市;2/28绿鞋 ≈HK$11.099bn 基础 40.8899m股 × HK$248 = HK$10.141bn;部分绿鞋 3.8658m股 × HK$248 ≈ HK$0.959bn IPO最终结果 · 绿鞋公告
15 华泰证券 6886 2/3 HK$10.0bn zero coupon、100%发行;8 Feb 2027到期;初始转股价HK$19.70,较前收premium 6.78%,较5日均价premium 5.09%;net HK$9.925bn。 HKEX CB完整条款
16 洛阳钼业 / CMOC 3993 1/19交易;1/20公告 US$1.2bn zero coupon、100%发行;24 Jan 2027到期;初始转股价HK$28.03,较前收premium 28.70%,较5日均价premium 26.17%。 HKEX CB完整条款

Source: ChatGPT

Evidence of deflation in China – %Arabica coffee

I met %Arabica Coffee in Hong Kong.

I liked it, especially the design of the coffee shop; I still kept its physical customer loyalty program card.

The coffee chain expanded in mainland China in 2018.

I have been to several of its stores in mainland China and it’s one of my favorites.

In mainland China, the %Arabica coffee loyalty program is more digital (I am using its mini-program on WeChat) and ran separately from the HK one.

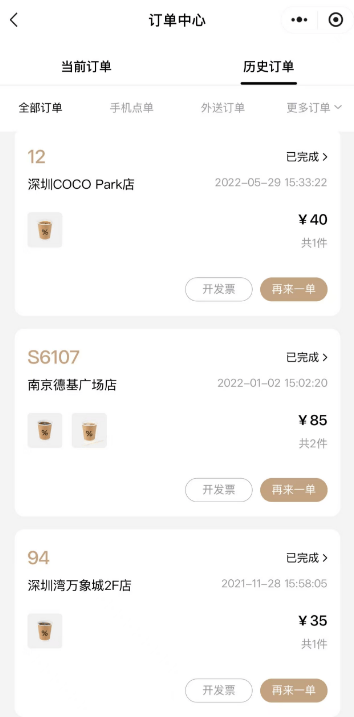
The mini-program kept my previous purchases and the Grande Ice Americano is 35 rmb.

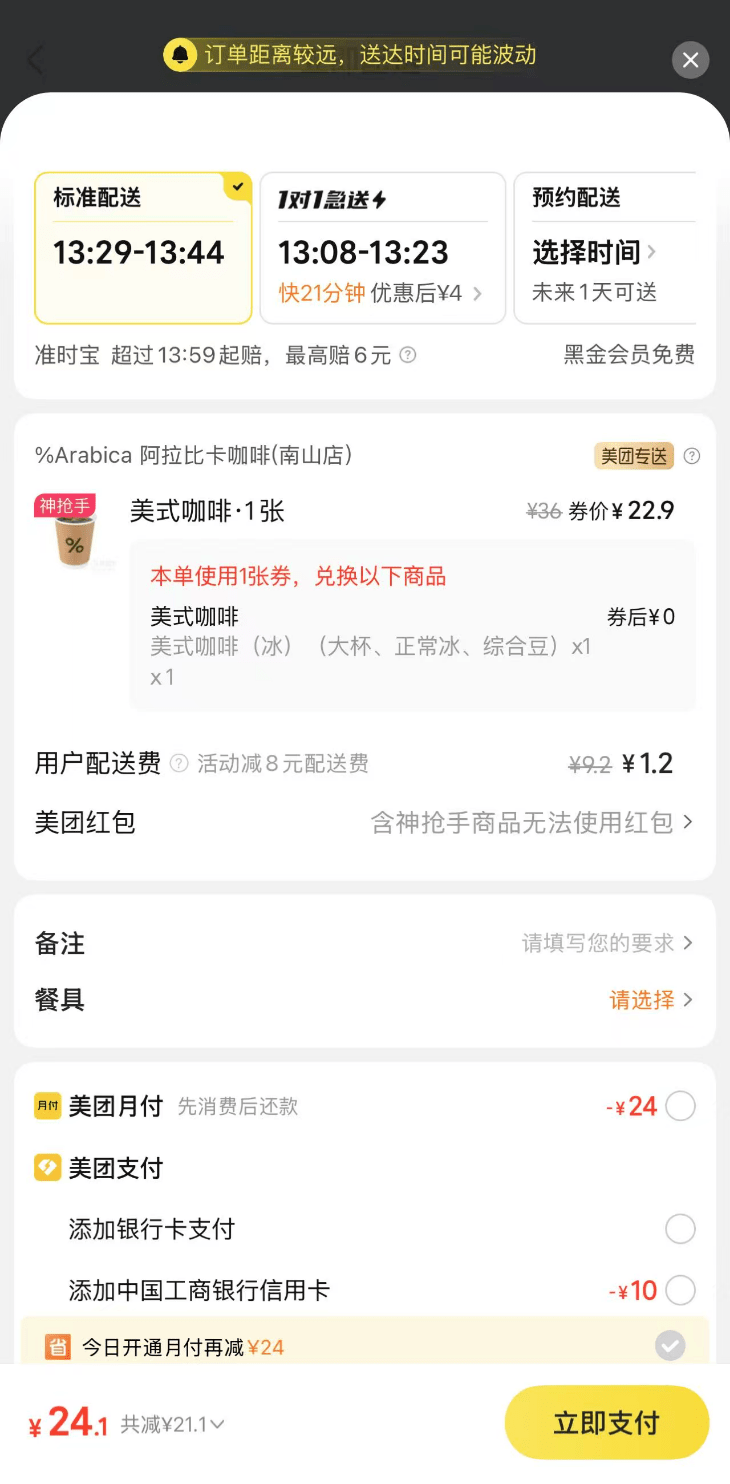
You know what, I am buying the %Arabica Grande Ice Americano with delivery to my door for 24 rmb (on weekend) !

As Meituan should also take a cut, the net price for %Arabica is much lower than 23 rmb.

That’s 1/3 cut for consumers and 40-50% cut for %Arabica!


That even makes the housing price decline in China “normal” and “not sufficient”.

Alibaba’s 3-year payback period

In Alibaba’s earnings call, it touted 3 years of payback and could improve that to 2.5 years or even 2 years.

That sounds strong.. but if you compare, that is nothing.

Even Luckin claims its franchisees have 1.5 – 2 years of payback periods.

And SpaceX said during recent 2q26 earnings that it has <1 year of payback period.

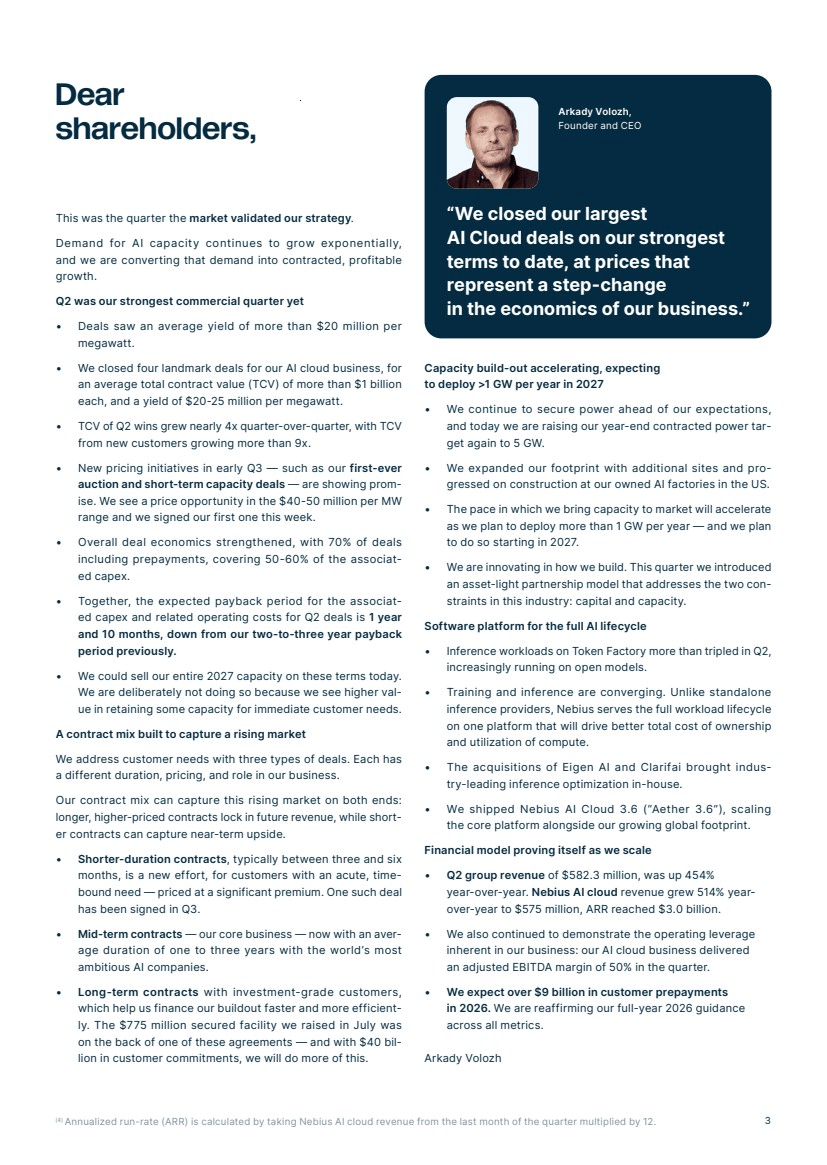
Nebius’s payback period is now 1 year and 10 months, down from 2-3 years, disclosed in 2q26 earnings.