中国地方政府为什么更喜欢“造东西”,而不是“让人消费”?// Why Do Chinese Local Governments Prefer Building Things Over Boosting Consumption?

一个很重要、但经常被忽略的原因,是税制激励。

中国现行增值税是中央和地方共享税。2016年营改增后,地方分享比例从25%提高到50%,而地方拿到的这部分收入,仍然很大程度上跟企业纳税地绑定。换句话说,一家汽车厂、电池厂、化工厂落在哪里,哪里不仅拿GDP、就业和投资,也能拿到持续的增值税税源。

这会自然强化地方政府的制造业偏好。

假设一个新工厂每年创造10亿元应缴增值税。过去地方可能只分到2.5亿元,2016年以后可以分到5亿元。再叠加企业所得税、城建税及各种附加,一个大型制造项目对地方财政的价值非常高。

于是地方政府最合理的行为,就是抢工厂、抢产能、抢总部、给土地、给融资、建产业园。单个地方这样做完全理性,但全国所有地方一起这样做,就容易形成重复投资和过剩产能。

反过来,一个居民多消费1000元,对当地政府的财政收益却没有那么直接。

比如上海居民买一辆安徽生产的车,制造企业缴纳的增值税税源主要仍跟企业纳税地相关。上海创造了最终需求,却未必能像生产地一样直接获得对应税收。

这就是中国税制一个很重要的结构性特征:

地方财政更奖励“生产发生在哪里”,而不是“消费发生在哪里”。

其实“消费地”并不一定难定义。实体商品可以按最终收货地,线下消费可以按门店所在地,汽车可以按上牌地;数字订阅没有收货地址,也可以按信用卡或支付账户的账单/KYC地址归属。规则不需要做到哲学意义上的100%准确,只要统一、稳定、可验证即可。

因此,中国并不一定需要简单加税。可以降低一部分现有VAT,同时把对应税率改成按最终消费地归属的sales tax;或者更简单,把现有地方VAT的一部分从“纳税地分配”改成“消费地分配”。

核心不是税叫什么名字,而是地方政府面对什么激励。

如果新增一座工厂能明显增加地方财政收入,而新增100亿元居民消费却不能,那么地方政府自然会继续优先招商、投资和扩产。

所以中国“重投资、重制造、轻消费”不仅是产业政策问题,也有很强的财政制度基础。

想真正刺激消费,除了给居民发钱,更重要的是让地方政府也能从消费增长中赚钱。


One important but often overlooked reason is the incentive created by China’s tax system.

China’s VAT is shared between the central and local governments. After the 2016 VAT reform, the local share rose from 25% to 50%. Crucially, much of that local revenue is still tied to where the company pays tax. So when an auto plant, battery factory, or chemical plant locates in a city, the local government gets not only GDP, jobs, and investment, but also a recurring VAT tax base.

That naturally strengthens the incentive to attract manufacturing.

If a new factory generates RMB1 billion of VAT a year, the local government might have received roughly RMB250 million before 2016 and RMB500 million afterward. Add corporate income tax, urban maintenance tax, and other surcharges, and a large manufacturing project becomes extremely valuable to local finances.

The rational response is obvious: compete for factories, capacity, headquarters, industrial parks, land investment, and financing support. That may be rational for each individual locality, but when every locality behaves the same way, the national result can be duplicated investment and excess capacity.

Consumption works differently.

If a Shanghai resident buys a car produced in Anhui, much of the VAT-related local revenue still follows the producer’s tax location. Shanghai creates the final demand, but it does not necessarily capture the corresponding marginal tax revenue in the same way Anhui does.

This creates a structural bias:

Local fiscal systems reward where production happens more than where consumption happens.

A consumption-based system does not necessarily have to be technically complicated. Physical goods could be sourced based on the final delivery address, offline services based on the store location, and cars based on the registration location. For digital subscriptions with no shipping address, the tax could be assigned using the billing or KYC address of the credit card or payment account.

The rule does not need to identify the philosophically perfect “true” place of consumption. It only needs to be uniform, stable, and verifiable.

China therefore would not necessarily need to raise taxes. One option would be to reduce part of the existing VAT and replace it with a sales tax allocated according to the final place of consumption. An even simpler option would be to keep the VAT system intact but redistribute part of the local VAT share based on consumption rather than the producer’s tax location.

The key question is not what the tax is called. It is what behavior the fiscal system rewards.

If building another factory clearly increases local government revenue, while another RMB10 billion of household consumption does not, local governments will naturally continue to prioritize investment, manufacturing, and capacity expansion.

China’s bias toward investment and manufacturing is therefore not only an industrial-policy issue. It is also embedded in the fiscal system.

If China wants to stimulate consumption structurally, it is not enough to give consumers more money. Local governments also need to make more money when consumption rises.

HK record financing

Alibaba now tops the list with 80bn HKD financing.

排名 公司 / 时间 规模 关键 Terms HKEX 官方公告
1 阿里巴巴 9988 8/23交易,8/24公告 HK$80.0bn 710m新股;HK$112.70;较参考股价折价约3.6%;扩大后占股本3.57%;net约HK$79.7bn;预计8/26交割。 HKEX 配售条款公告
2 中际旭创 3308 7/30上市 HK$53.410bn IPO 54.5m股 × HK$980;net HK$52.891bn;另有8.175m股绿鞋,但该HK$53.41bn数字未计绿鞋。 HKEX 最终发售价及配发结果
3 宁德时代 3750 4/28 HK$39.190bn 配售 62.385m H股 × HK$628.20;较前收折价7.0%,较5日均价折价10.46%;扩大后稀释约1.36%。 HKEX 配售条款公告
4 智谱 2513 7/9 HK$31.411bn 最多 19.78m H股 × HK$1,588;较前收折价12.99%,较5日均价折价6.72%;扩大后约4.25%。 HKEX 配售条款公告
5 立讯精密 2475 7/9上市;8/5绿鞋 ≈HK$25.060bn 基础 383.473m股 × HK$63.28 = HK$24.266bn;8/5部分绿鞋 12.542m股 × HK$63.28 ≈ HK$0.794bn。 IPO最终结果 · 绿鞋公告
6 胜宏科技 2476 4/21上市;4/22绿鞋 ≈HK$23.135bn IPO最终95.85m股、HK$209.88,基础gross HK$20.117bn;随后全额绿鞋14.3775m股,同价发行。(HKEX News) IPO最终结果 · 全额绿鞋公告
7 美的集团 0300 5/6定价;5/7公告 HK$17.248bn 两档各HK$8.624bn、均zero coupon、100%发行。2027档:到期11 May 2027、转股价HK$96.82;2033档:到期13 May 2033、转股价HK$115.76,到期赎回114.95%。 HKEX 双档CB完整条款
8 MiniMax 0100 7/10 HK$16.041bn 配售:35.6m股 × HK$268 = HK$9.541bn;另发 HK$6.5bn zero-coupon CB,100%发行,约7/14/27到期,初始转股价HK$335,较前收premium 12.64%,到期赎回102.75%。 HKEX 配售+CB完整条款
9 联想集团 0992 6/17交易;6/18公告 US$2.0bn zero coupon、100%发行、7年期,到期25 Jun 2033;初始转股价HK$36.70,较签约日收盘价premium约47.5%;net约US$1.979bn。 HKEX CB完整条款
10 MMG 1208 6/16 HK$6.268bn + US$0.8bn CB 配股 705.892m股 × HK$8.88;另发US$800m zero-coupon CB,发行价102%,所以CB gross cash为US$816m;21 Jun 2027到期;初始转股价HK$10.21。 HKEX 配售+CB完整条款
11 牧原股份 2714 2/6上市;3/5绿鞋 ≈HK$12.099bn 基础 273.9514m股 × HK$39 = HK$10.684bn;3/5部分绿鞋 36.2717m股 × HK$39 ≈ HK$1.415bn。 IPO最终结果 · 绿鞋公告
12 紫金矿业 2899 1/29交易;1/30公告 US$1.5bn face / US$1.5375bn gross zero coupon;发行价102.5%;5 Feb 2031到期;初始转股价HK$63.30,较前收premium 37.19%、5日均价premium 45.92%。(HKEX News) HKEX CB完整条款
13 中国宏桥 1378 4/28 RMB10.2bn USD-settled zero coupon CB;100%发行;3 May 2027到期;初始转股价HK$43.90。 HKEX CB完整条款
14 东鹏饮料 9980 2/3上市;2/28绿鞋 ≈HK$11.099bn 基础 40.8899m股 × HK$248 = HK$10.141bn;部分绿鞋 3.8658m股 × HK$248 ≈ HK$0.959bn。 IPO最终结果 · 绿鞋公告
15 华泰证券 6886 2/3 HK$10.0bn zero coupon、100%发行;8 Feb 2027到期;初始转股价HK$19.70,较前收premium 6.78%,较5日均价premium 5.09%;net HK$9.925bn。 HKEX CB完整条款
16 洛阳钼业 / CMOC 3993 1/19交易;1/20公告 US$1.2bn zero coupon、100%发行;24 Jan 2027到期;初始转股价HK$28.03,较前收premium 28.70%,较5日均价premium 26.17%。 HKEX CB完整条款

Source: ChatGPT

Evidence of deflation in China – %Arabica coffee

I met %Arabica Coffee in Hong Kong.

I liked it, especially the design of the coffee shop; I still kept its physical customer loyalty program card.

The coffee chain expanded in mainland China in 2018.

I have been to several of its stores in mainland China and it’s one of my favorites.

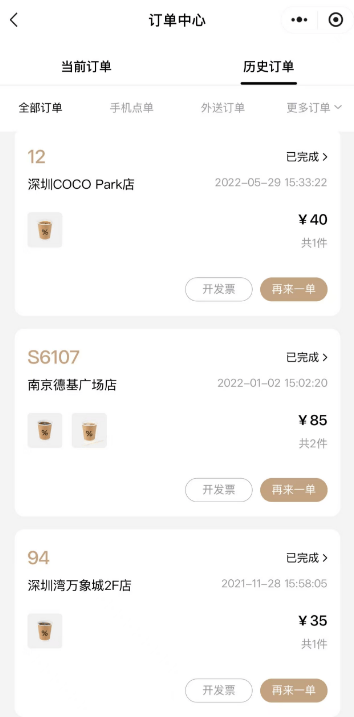
In mainland China, the %Arabica coffee loyalty program is more digital (I am using its mini-program on WeChat) and ran separately from the HK one.

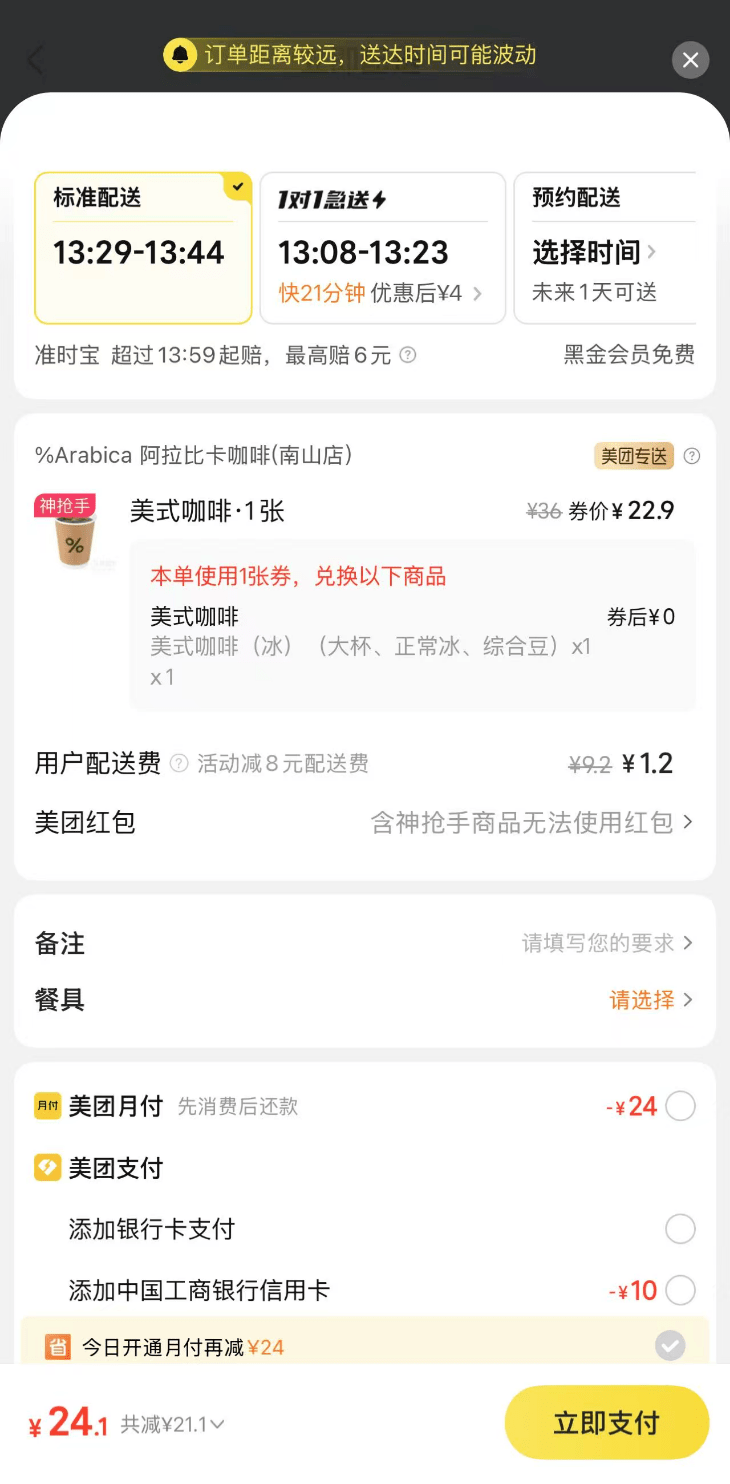
The mini-program kept my previous purchases and the Grande Ice Americano is 35 rmb.

You know what, I am buying the %Arabica Grande Ice Americano with delivery to my door for 24 rmb (on weekend) !

As Meituan should also take a cut, the net price for %Arabica is much lower than 23 rmb.

That’s 1/3 cut for consumers and 40-50% cut for %Arabica!


That even makes the housing price decline in China “normal” and “not sufficient”.

Alibaba’s 3-year payback period

In Alibaba’s earnings call, it touted 3 years of payback and could improve that to 2.5 years or even 2 years.

That sounds strong.. but if you compare, that is nothing.

Even Luckin claims its franchisees have 1.5 – 2 years of payback periods.

And SpaceX said during recent 2q26 earnings that it has <1 year of payback period.

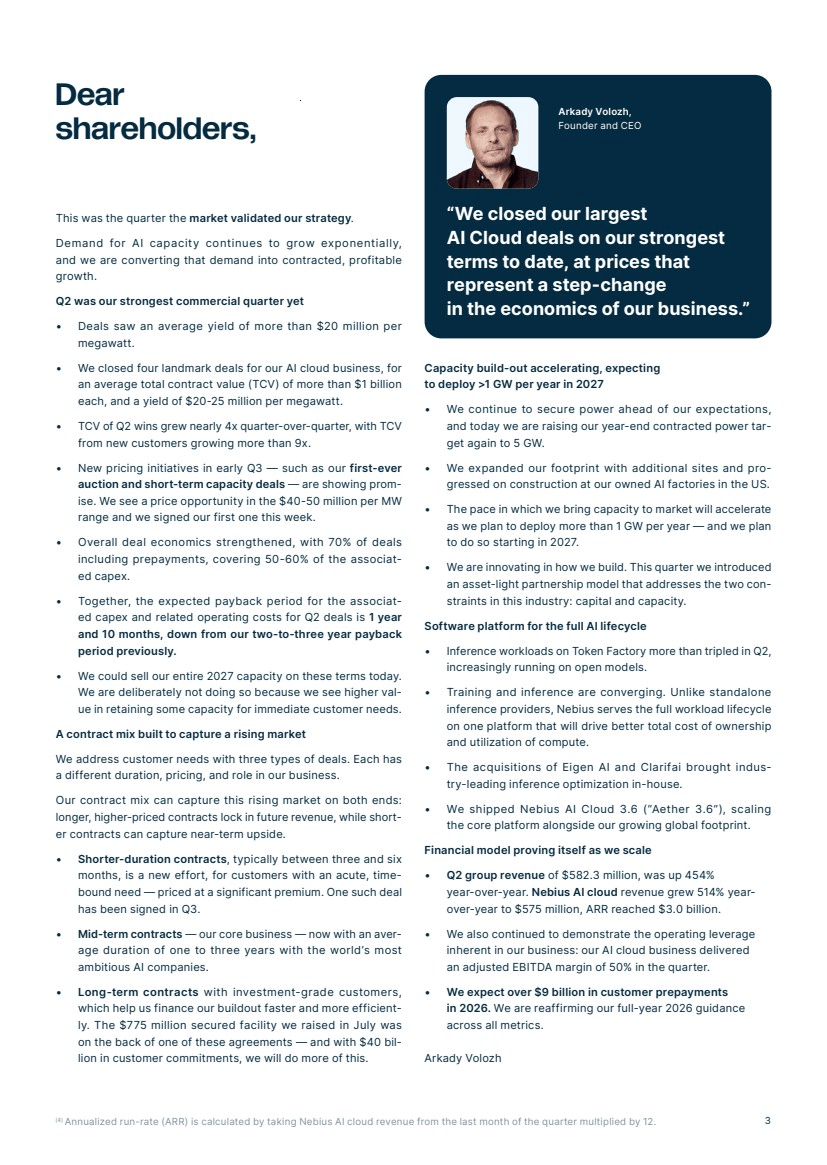
Nebius’s payback period is now 1 year and 10 months, down from 2-3 years, disclosed in 2q26 earnings.


Diverging path: Baidu vs. Google

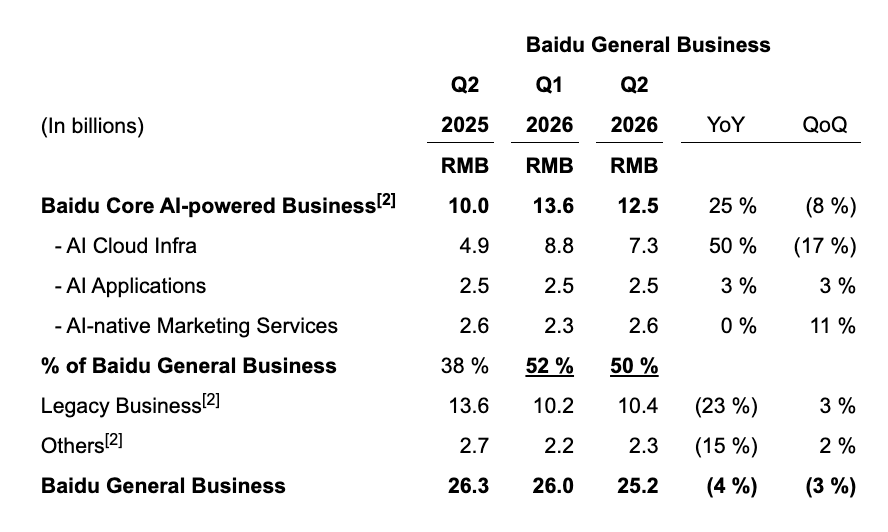
In Q2 2026, Baidu online marketing revenue fell 19% YoY to RMB13.1bn, after falling 22% in Q1.

And AI-native ads doesn’t seem impressive.

Meanwhile Google Search & Other revenue grew 17% YoY to $63.3bn in 2q26.

Google search revenue didn’t feel much impact from growing usage of chat AI.

One difference, probably unrelated to AI-era, is that content sits inside giant closed ecosystems, much of which Baidu either can’t index properly or isn’t the natural starting point for.

Consumers can go directly to vertical apps. This is especially true when mobile is more important than web in China.

Baidu is simply not the end of a discovery journal, while Google still is.

Even if you chat with AI, you might still go to Google to do final checks or to look for places to do the transaction.

Another issue is that Google AI Overview seems more successful in monetization.

Baidu management says it is “deliberately holding back” AI-search monetization.

Google previously disclosed that queries showing AI Overviews monetized at approximately the same rate as traditional Search, and in Q2’26 said it continued to be encouraged by AI Overview monetization even as it expanded into more commercial queries.


China’s recycled rocket

“Recovered” is not yet the same as “reused”.

1/ China recovered the first stage, not the entire rocket.

2/ Only after a successful second flight with that same booster can China demonstrate operational reuse.

The first stage contains most of the rocket’s engines and represents a large share of its manufacturing cost.

Net-based capture system: rocket does not need to carry conventional landing legs, their deployment mechanisms, and as much associated structural reinforcement throughout the flight.

However, the heavy landing legs is more reusable outside of earth more easily I assume – especially for the first time for a planet.


PetroChina A-Share IPO


Chapter 1 – The World’s Fastest-Growing Economy

At the beginning of the 21st century, China was transforming faster than any major economy in modern history.

After joining the WTO in 2001, factories spread across the country. Steel mills, cement plants, highways, airports and apartment towers appeared almost overnight. GDP grew at roughly 10–14% annually. Millions of people bought cars for the first time. Every additional factory required electricity; every truck consumed diesel; every construction site demanded asphalt.

China’s oil consumption reflected this transformation.

Between 2000 and 2007, Chinese oil demand nearly doubled, growing from roughly 4.8 million barrels per day to over 7.5 million barrels per day. China became the second-largest oil consumer in the world after the United States.

At the same time, global supply struggled to keep pace.

Years of underinvestment following the late-1990s oil collapse left little spare production capacity. Geopolitical risks—including the Iraq War, unrest in Nigeria, and concerns about Iran—added further uncertainty. Commodity investors began describing the period as the beginning of a “commodity supercycle.”

Crude oil rose relentlessly:

  • 2002: around US$20–30/bbl
  • 2004: above US$40
  • 2005: above US$60
  • 2006: around US$70
  • Mid-2007: above US$75
  • July 2008: eventually reaching US$147/bbl

To many investors, there seemed to be only one conclusion:

China would continue growing forever.

Oil prices would continue rising forever.

Therefore, oil companies would become permanently more profitable.


Chapter 2 – The Perfect National Champion

Among Chinese companies, none symbolized this story better than PetroChina.

Unlike many newly listed private companies, PetroChina represented ownership of China’s most strategic industry.

It controlled massive upstream oil reserves, pipelines, refineries and distribution assets.

To domestic investors, buying PetroChina meant buying China’s economic miracle itself.

The company had already listed H-shares in Hong Kong in 2000 and ADRs in New York.

However, most mainland investors could not easily purchase overseas shares.

The A-share IPO therefore became something entirely different:

For the first time, ordinary Chinese investors could own what many considered the country’s most valuable enterprise.

Demand became extraordinary.


Chapter 3 – The Bubble Already Existed

By late 2007, Chinese equities were already experiencing one of history’s largest valuation bubbles.

The Shanghai Composite had risen from roughly 1,000 points in mid-2005 to more than 6,000.

Retail investors opened brokerage accounts at record speed.

Newspapers discussed stocks on front pages.

Taxi drivers and university students debated IPO allocations.

People queued outside brokerage offices.

Mutual funds sold out within hours.

There was widespread belief that the Chinese government would never allow the stock market to fall significantly.

Liquidity flooded into every large IPO.


Chapter 4 – Valuation Lost Contact With Reality

Internationally, oil companies remained reasonably valued despite high oil prices.

Approximate valuation before the PetroChina A-share IPO:

Company Forward P/E (approx.)
ExxonMobil 10–12×
Chevron 9–11×
BP 9–10×
Shell 9–11×
Total 9–11×

Investors largely assumed oil prices would eventually normalize.

Chinese investors reached a completely different conclusion.

The PetroChina A-share IPO was priced at RMB16.70.

On its first trading day:

  • Open: RMB48.60
  • Intraday high: RMB48.62
  • Close: RMB43.96

At the day’s high, PetroChina briefly became the world’s largest listed company by market capitalization, exceeding US$1 trillion.

Yet the underlying business had not changed.

The same oil fields.

The same refineries.

The same earnings.

Only the market where investors traded the shares had changed.

The implied valuation was estimated at roughly 45–60× earnings depending on methodology—roughly four to six times the multiple of global oil majors.

This was not because PetroChina was dramatically more profitable than ExxonMobil.

It was because investors believed China’s growth would remain extraordinary forever.


Chapter 5 – Scarcity Meets National Optimism

Several forces reinforced one another.

China’s GDP was booming.

Oil prices were making new highs almost every month.

The Shanghai market itself was already euphoric.

Mainland investors had limited investment alternatives.

PetroChina represented both national pride and perceived scarcity.

Many investors believed:

“If China’s economy doubles again, PetroChina must also double.”

Few asked the more important question:

“What if today’s profits already assume exceptionally high oil prices?”

The distinction between a great company and a great investment disappeared.


Chapter 6 – The Peak

On November 5, 2007, PetroChina reached its all-time A-share high during its first minutes of trading.

It would never revisit that price.

Only months later, the global financial crisis began unfolding.

Oil prices collapsed from US$147 to below US$40.

Commodity profits normalized.

Shanghai Composite Index fell by more than 70%.

PetroChina’s valuation gradually converged toward international oil majors.

The company remained one of China’s largest and most important enterprises.

The business largely survived.

The valuation did not.


Epilogue – The Last Buyer

The PetroChina A-share IPO remains one of history’s clearest examples of the difference between a wonderful company and a wonderful stock.

Almost every part of the bullish narrative proved true:

  • China continued becoming a global economic superpower.
  • Oil demand continued growing for years.
  • PetroChina remained enormously profitable.
  • The company remained strategically indispensable.

Yet investors who purchased at the IPO peak suffered enormous long-term losses because they paid a valuation that assumed an almost perfect future.

The lesson was never that PetroChina was a poor business.

The lesson was that even the greatest businesses can become poor investments when narrative, liquidity, scarcity and optimism combine to overwhelm valuation.

That distinction continues to echo in every market cycle—from technology in 2000, to Chinese equities in 2007, to other periods when investors begin believing that “this time is different.”

Xiaomi buybacks and share sales in history

Xiaomi has been doing buybacks with stock price falling, e.g.

June 22 bought back 6.42m shares for HK$152mn, avg. price at HK$23.68

June 23 bought back 8.44m shares for HK$193mn, avg. price at HK$22.86

People joked that Xiaomi is quite good at buying and selling its own shares.

How good is Xiaomi?

1/ When Xiaomi stock was at more depressed levels (2022 & 2023), it didn’t buy back more aggressively.

In 2021, Xiaomi bought back at avg. HKD 24.5 per share; spent about 8.4bn HKD.

In 2023, when Xiaomi stock is only half of 2021 buyback price, Xiaomi spent 1.5bn HKD in buyback, which is 18% of 2021 in dollar amount.

The number of shares bought back decreased year over year from 2021 to 2023: 344mn -> 235mn -> 127mn.

2/ Xiaomi is good at selling.

The company sold 800 million shares at HK$53.25 each in March 2025; raised $5.5 billion.

In Dec 2020, Xiami sold 1.0bn Class B shares at HK$23.70 per share, plus $855 million through seven-year, zero-coupon convertible bonds, raising $4 billion in total.

—

Be careful – when Xiaomi resumed buybacks in late 2025 and stepped up in 2026, it’s good but it doesn’t mean much – it could be like 2021.