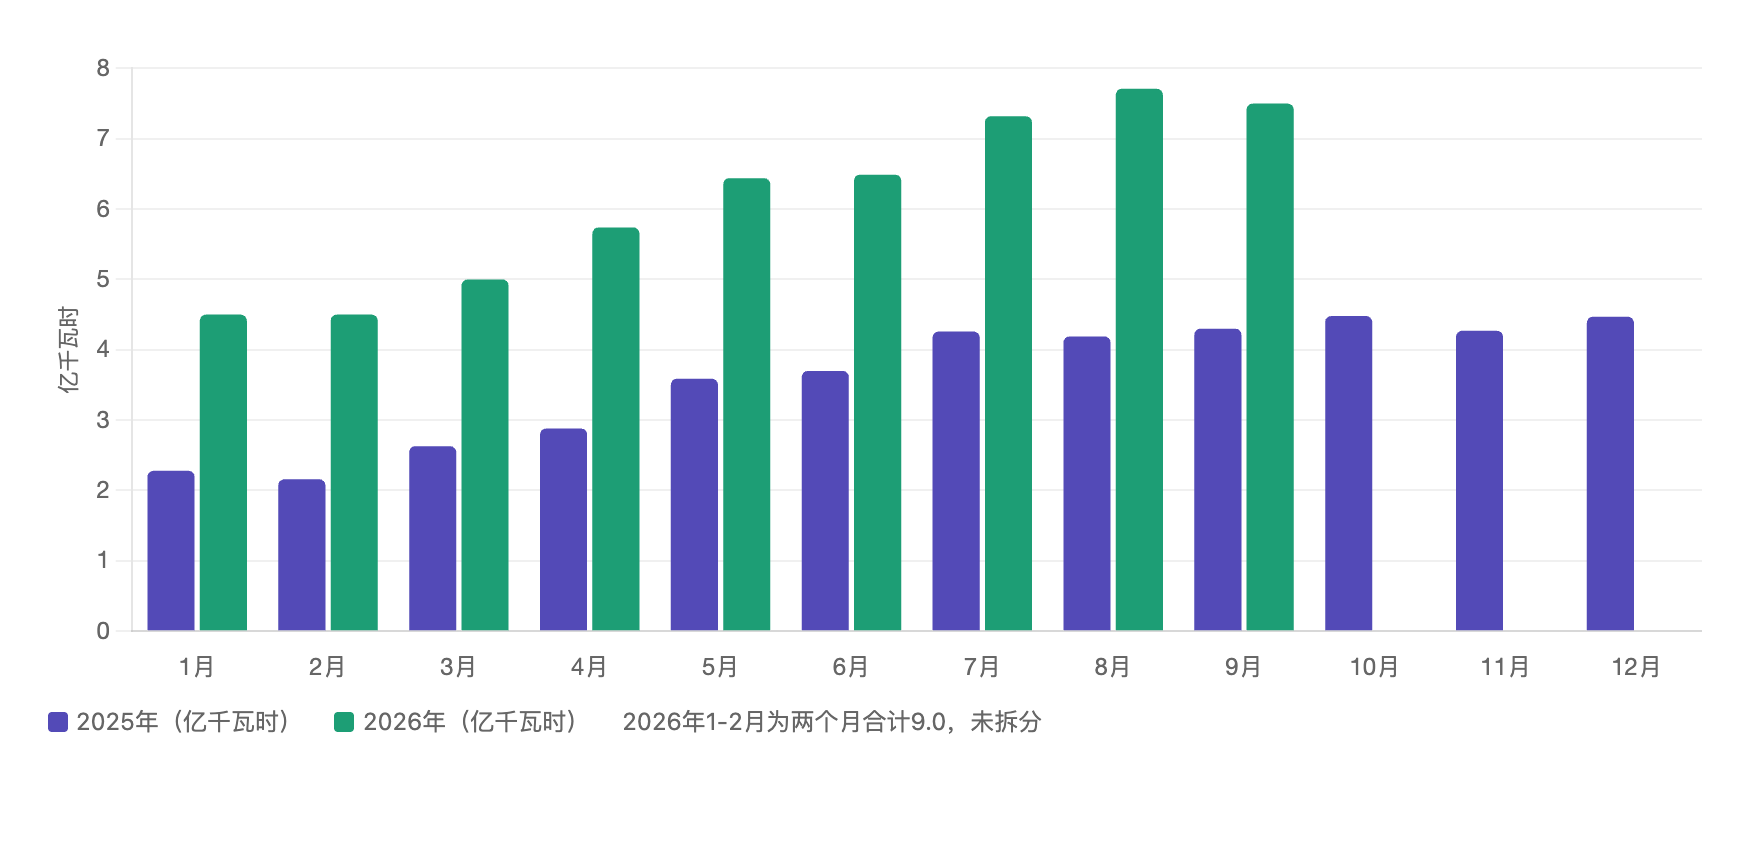
Ulanqab electricity usage (data centers)

Ulanqab has become one of the most important hubs for China (AI) data centers now.

Government official data is a reliable source of its electricity consumption growth.

2026 Jan and Feb are reported together.


Data

Month GWh GW % yoy
2025-01 228 0.31
2025-02 216 0.32
2025-03 263 0.35
2025-04 288 0.4
2025-05 359 0.48
2025-06 370 0.51
2025-07 426 0.57
2025-08 419 0.56
2025-09 430 0.6
2025-10 448 0.6
2025-11 427 0.59
2025-12 447 0.6
2026-01 450 0.63
2026-02 450 0.66 102.8% (together with Jan)
2026-03 500 0.67 90%
2026-04 574 0.8 99%
2026-05 644 0.87 79%
2026-06 649 0.9 75%
2026-07 732 0.98 72%
2026-08 771 1.04 84%
2026-09 750 1.04 74%

Capex peaking

Oracle capex to peak in FY28, or Jun 2027–May 2028.

Following a period of peak capex in FY27-FY28, capital expenditures are expected to step-down in FY29.

– Oracle Investor Day Oct. 28, 2026


MSFT capex missed. Microsoft guided capex for next q is $50bn vs expectation of $53bn, while reported capex for current quarter is $39bn vs expected $46bn.

And MSFT mentioned higher return on capex in future.

we continue to improve the efficiencies of our infrastructure, each dollar of CapEx has the potential to support more revenue and higher returns over time

– Microsoft Fiscal 2027 first quarter earnings call

Sounds to me that capex efficiency is bottoming, which could mean price appreciation in hardware is peaking.


Google stock didn’t do well with higher capex comments in FY2027, although stock is also under pressure with Google ads, which is under threat from AI.

Sovereign debt

Sovereign debt is becoming an topic lately with rising yield and France is under the spotlight.

What is considered “dangerous” in sovereign debt?

Probably not just high debt-to-GDP ratio… because Japan is over 200% on the ratio (highest among G20), but is typically not considered the most dangerous.

Japan debt is mostly in yen and held by domestic investors.

I think also need to consider gov revenue as % of GDP and net debt vs gross debt.

Asked ChatGPT and it give me this.

Given Japan’s investor base and USD’s global status, it looks like Indonesia, South Africa are the most dangerous, while Italy and UK are the most dangerous among developed countries.


General government; latest available 2025 figures, except Japan and South Korea (2024). Ranked highest to lowest.

Rank Country Net debt / GDP Revenue / GDP Net debt / revenue
1 Japan* 141.1% 35.5% 3.98x
2 United States 96.7% 30.5% 3.17x
3 Indonesia 38.5% 13.3% 2.90x
4 South Africa 75.7% 28.5% 2.66x
5 Italy 127.7% 48.1% 2.65x
6 United Kingdom 93.6% 38.2% 2.45x
7 Mexico 53.2% 25.0% 2.13x
8 France 108.4% 52.2% 2.08x
9 Brazil 66.8% 39.5% 1.69x
10 Germany 47.1% 47.2% 1.00x
11 Saudi Arabia 22.6% 23.3% 0.97x
12 Australia 33.9% 36.7% 0.92x
13 Türkiye 18.0% 29.5% 0.61x
14 Canada 10.4% 42.3% 0.25x
15 South Korea* 8.1% 32.0% 0.25x
— China N/A 25.0% N/A
— India N/A 20.9% N/A
— Argentina N/A 31.0% N/A
— Russia N/A 35.3% N/A

Sources: IMF WEO net-debt series and general-government revenue series, via IndexBox and The Economy Pulse. Ratios calculated from rounded inputs. *Japan and South Korea use 2024 data because matched 2025 revenue and net-debt observations were not independently verified. The figures are indicative and underlying publication vintages may differ.


Housing prices after stock market bubble

2000

Buying a U.S. home in 2000 and selling it in 2003 would generally have been very profitable, even as the dot-com bubble collapsed. According to the Case-Shiller U.S. National Home Price Index, home prices increased approximately 28% over those three years, or about 8.5% annualized.

Unlike in the U.S., buying residential property in Tokyo, Singapore or Hong Kong in 2000 and selling in 2003 would generally have lost money.

Chart by ChatGPT

2021

Buying a home in 2021 and selling in 2024 was profitable in the U.S., Tokyo and Singapore, but disastrous in Hong Kong.

Chart by ChatGPT


Some nuances

  • Policy. The Bush administration actively promoted homeownership after the dot-com crash, particularly from 2002 onward
  • Hong Kong and Singapore suffered from SARS in 2003
  • Hong Kong suffered from China geopolitical tension with US/western countries in 2021-24 cycle

BRICS leaders don’t retire

Lula won reelection, securing his fourth presidential term with 51.79% of the vote against Flávio Bolsonaro.

What about other leaders

Current leader Years in top leadership* Expected or mandatory exit
Putin 🇷🇺 27 Eligible to serve until 2036
Xi 🇨🇳 14 No formal term limit
Modi 🇮🇳 12 No term limit; next election due 2029
el-Sisi 🇪🇬 12 Current constitutional endpoint 2030
Lula 🇧🇷 12 cumulative Current term ends 2026
Mohammed bin Salman 🇸🇦 9 as Crown Prince No fixed retirement
Ramaphosa 🇿🇦 9 Presidential limit applies
Abiy Ahmed 🇪🇹 9 No PM term limit
Mohamed bin Zayed 🇦🇪 4 as president Unlimited reelection
Pezeshkian 🇮🇷 2 Presidential term limits apply
Prabowo 🇮🇩 2 Maximum two presidential ter

ms

*Putin’s figure includes time as prime ministe; Mohammed bin Salman’s with becoming Crown Prince.

Everyone wants liquidity – that could be a problem

Anthropic is about to go IPO in November; its 3q26 revenue is ~$16.8bn, up 45% qoq. With target valuation rumored around $1.5-2 trillion, it can raise $75 billion or more with 5% dilution.

SpaceX raised $75bn in its IPO in Jun.

Google raised more than $40bn in Jun, including $10bn from Berkshire, $15bn in equity (upsized to $18bn) and $15bn in convertible bonds (upsized to $16.75).  Google has another $40bn ATM equity offering that it hasn’t raised.

Meanwhile, Meta said it plans to raise up to $95 billion in equity.

OpenAI is closing in on a private funding round of up to $30 billion at a pre-money valuation of $1.25 trillion.

DeepSeek just raised approximately $15 billion (about 100 billion yuan) in its private funding round.


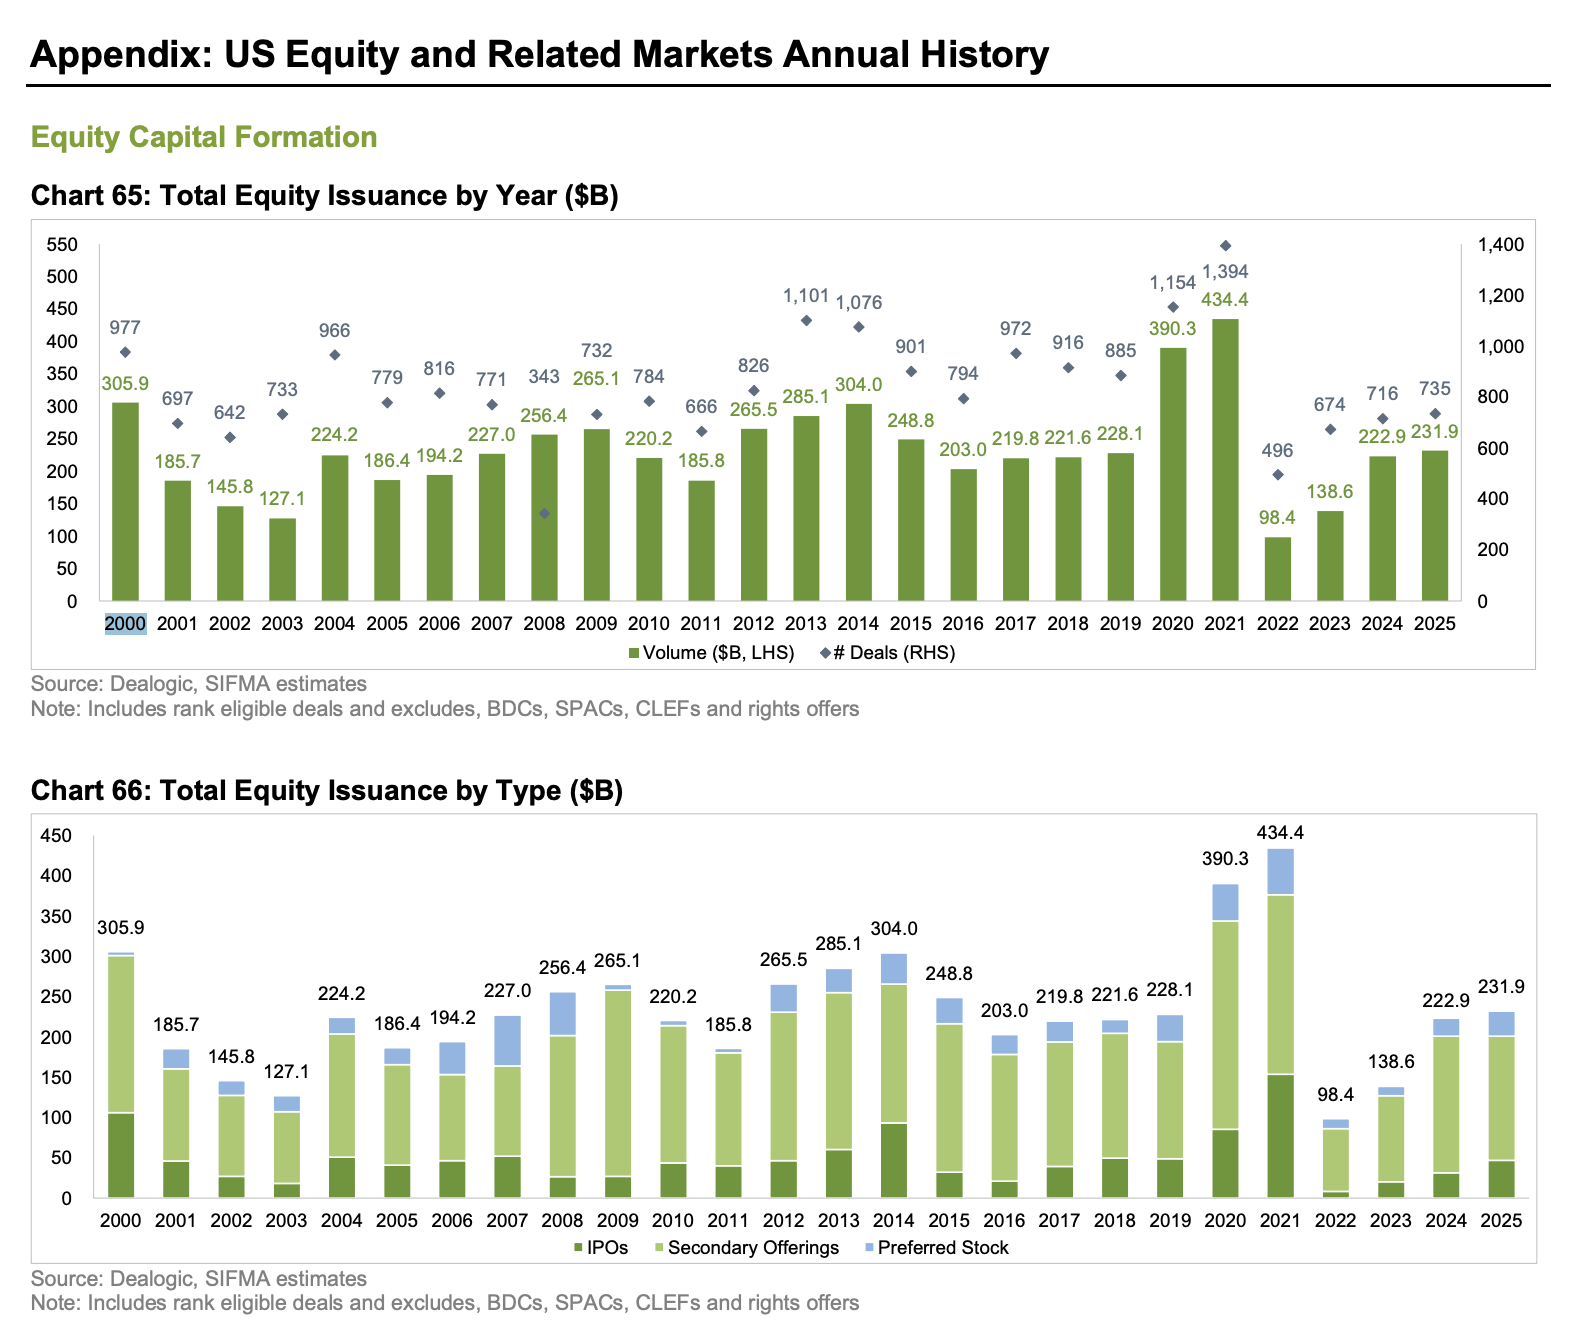
For 2026 through September, US public equity market raised $355.1bn.

To compare, US public equity market raised $300bn in 2000, or 3% of US GDP.

If add public and private equity raise, 2000 equity raise reaches 4% of GDP.

Currently, if 4q26 equity raise reaches $400bn, it will make 2026 private+public equity raise exceed 4% of US GDP.

So far, notable deals already push the number to over $1.1 trillion of 3.5% of US 2026 GDP.

Historically, 3% is not common; 4% or near 4% can be dangerous.


Higher tax for wealthy in US and China

This has become a hotter topic lately as some attributes the stock decline to it.

On the China side, people are increasingly aware of the additional off-shore trust tax (2026年21号离岸信托公告 & 15号配套征管文件). The rules are effective as of July 24, 2026. For individuals covered by the rules, the principal tax rate is 20%, generally applied to gains, dividends and when transferring assets into an offshore trust.

On the US side, California wealth tax is being discussed. Proposition 40 would impose a one-time 5% wealth tax on California billionaires, including the value of their stocks, private businesses, investment portfolios and other taxable assets, as of Dec 31, 2026. It is on the November 3, 2026 ballot, targeting people who were California residents on January 1, 2026. A simple majority is required to pass Proposition 40, and it is subject to interaction with Props 41 and 42, which prohibit the change in tax.

The implications of higher taxes are profound here.

1/ Additional taxes cause market liquidity crunch – few people keep a lot of cash on the sideline.

2/ The market value is arbitrary. Lowering the market value / stock price will do the job. This creates additional downside risks.

3/ To me, tax is not something that should be easy to change. It’s part of the social fabric or “contracts”. This incentives people to do other unnecessary things.

However, we also need to realize that taxing wealth that ordinary income taxes do not fully capture is a thing that needs more attention.

I assume this may be a direction that many other places may welcome and try to duplicate.

Meanwhile, we might need innovative ways to tax other than ordinary income, or lower the tax on ordinary income to bridge the gap.
Ken might have picked the wrong fight

Sure, AI might be in a bubble.

But AI giants today can crush big guys in financial industry.

Companies like Citadel and Citadel Securities compete with peers on talents and infra.

Infra is more influenced by compute and thus controlled by AI giants.

Talents will gradually be competed away by better AI models, support by AI giants.

So it does seem to me that if AI giants want to support someone that is friendlier towards AI, the can tilt the lanscape.

Local governments in China investing

1/

The relationship between a company’s management and local political leaders can be a material, underappreciated investment factor in China.

A. Political connections have measurable economic value

Mechanism Benefit of strong relationships Risk when relationships weaken
Bank financing Easier credit coordination and refinancing Tighter credit, higher funding costs
Local infrastructure Faster power, land and construction coordination Delays and additional capex
Government contracts Better access to investment and procurement opportunities Lost orders or weaker contract pipeline
Subsidies More favorable funding allocation Reduced grants and incentives
Problem resolution Faster coordination among multiple agencies Administrative delays
Competition Better access to scarce local resources Competitors gain priority
Financial distress Potential help coordinating restructuring Creditors become less accommodating

B. Leadership turnover could be catalysts.

A study found that local Party secretary turnover increased firm-specific stock crash risk, particularly among private and less transparent companies.

Meanwhile, officials may be promoted, and thus benefit supported companies more; or officials move across country so that companies get into different markets etc.

2/

Forces and relationships between local governments can create interesting phenomenon.

Every city has an incentive to compete for investment, even though they would collectively benefit from less expansion. Even an industry is oversupplied or has low return, a city gets the investment, jobs, tax base and industrial ecosystem.

Other dynamics include local protectionism. A listed company can have superior products and lower costs yet lose procurement contracts because a local government wants to support employers and taxpayers in its jurisdiction. This is particularly relevant to municipal SOE purchasing, government IT, buses, public-sector vehicles and some types of industrial equipment.