Blog

Leaders that don’t retire vs leaders who empower others

Following previous posts on BRICS leaders amazingly long tenure, I just realized that other positions may have similar issues.

Those who don’t retire are a group of people!

Non-BRICS country leaders like Trump.

Nvidia Jensen Huang.

Tesla/SpaceX Elon Musk.

Meta Mark Zuckerberg.

Anthropic Dario Amodei.

While Zuckerberg and Amodei are still under 45, others may be challenged on this question.

A healthy organization needs to have good candidates to lead in next era – a good leader needs to empower and mentor a generation of leaders.

George Washington is a good example.

Apple is a good example.

Nvidia after Alice Huang

Read my previous post: How Nvidia stock is like Apple and what may come next


My comments after Alice Huang incident:

1/ AI won’t stop from here; it’s probably healthier to have other (leaders’) voices besides Jensen Huang; it’s better to have more choices

2/ stock market is better with less focus on AI infra and less inflation in components; it makes much more sense now

3/ national security is probably less of a real concern; it’s much more important to have more “say” or leverage in Nvidia and AI.


Ten predictions by ChatGPT


1. The white-collar employment crisis arrives without a recession

60%

Labor market / society

AI reduces entry-level hiring much faster than it reduces overall employment. Graduate recruitment in consulting, accounting, software, legal services and financial services falls sharply.

The surprise: unemployment remains relatively low, but the traditional career ladder breaks. This creates a political problem that conventional unemployment statistics fail to capture.

Evidence is already emerging: a Dallas Fed study found weaker employment outcomes for graduates from AI-exposed majors, while Census research identified a persistent decline in early-career hiring in exposed industries.

Federal Reserve Bank of Dallas+1


2. Private credit experiences its first major liquidity shock

40%

Financial stability

At least one large private-credit vehicle faces redemption requests substantially above its permitted withdrawal limits, forcing gates and material asset markdowns.

The surprise: private credit was supposed to be insulated from daily market volatility. But semi-liquid products have introduced liquidity promises against illiquid assets.

The IMF estimates a roughly $2 trillion direct-lending market, including approximately $300 billion in semi-liquid structures. The Fed has already documented rising redemption requests.

International Monetary Fund+1


3. Home insurance becomes the next housing crisis

45%

Real estate / climate

Insurance availability, rather than mortgage rates, becomes the binding constraint on homeownership in certain US regions.

My prediction: multiple regional housing markets experience significant repricing because homeowners cannot obtain affordable insurance, making properties harder to finance and sell.

The GAO already finds inflation-adjusted insurance premium increases of 25% or more in certain high-risk coastal areas during 2019–2024.

U.S. GAO


The second-order effect is more important: mortgage collateral becomes less valuable.

4. A food inflation shock arrives despite falling energy prices

40%

Agriculture / geopolitics

The strong El Niño forecast for 2026–27 produces more severe agricultural disruption than markets anticipate.

I expect at least one major food commodity to rise more than 25% from its November 2026 level during 2027, accompanied by export restrictions or emergency food subsidies somewhere in the world.

NOAA expects a strong-to-very-strong El Niño through early 2027. Crop monitoring agencies already identify elevated drought and crop-yield risks in several regions.

Climate Prediction Center+1


This could create a surprising divergence: falling oil prices but rising food inflation.

5. The first in-vivo gene-editing medicine gets FDA approval

60%

Biotechnology / medicine

A major milestone in gene editing moves from clinical research into commercial medicine.

Intellia Therapeutics’ lonvo-z, an in-vivo gene-editing candidate for hereditary angioedema, has an FDA priority-review target date of March 10, 2027.

This is potentially a platform milestone: genetic editing inside the human body rather than modifying cells outside the body and returning them to the patient.

SEC


The broader surprise would be that the market starts valuing gene editing as a repeatable therapeutic platform rather than a collection of speculative individual drug candidates.

6. Satellite connectivity starts challenging the traditional telecom model

40%

Telecommunications / space

Ordinary smartphones increasingly connect directly to satellites for basic connectivity, without dedicated satellite phones.

By the end of 2027, I expect at least two major mobile markets to establish mainstream direct-to-device offerings.

The important catalyst is the 2027 World Radiocommunication Conference, where international spectrum rules for direct-to-device connectivity will be discussed.

GSMA


The longer-term implication: mobile operators may need to rethink the economics of rural coverage and roaming.

7. France triggers a major European sovereign-bond scare

25%

Politics / European integration

The 2027 French presidential election produces a fragmented political outcome and renewed concerns about fiscal sustainability.

My tail scenario: French 10-year government bond spreads over Germany exceed 200 basis points, at least temporarily.

This would not necessarily mean a euro breakup. The more likely consequence would be a new debate over fiscal rules, ECB intervention and European political integration.

France’s election is scheduled for April and May 2027, against an already difficult fiscal backdrop.

Allianz+1


8. Deepfake fraud forces a fundamental redesign of digital identity

40%

Cybersecurity / social trust

A major financial fraud involving convincing AI-generated video, voice and identity documents triggers a regulatory response.

Governments and financial institutions increasingly require cryptographic identity verification for high-value transactions and sensitive digital interactions.

The US Treasury has already documented AI-generated identities being used to bypass financial institutions’ customer-identification checks.

U.S. Department of the Treasury


The surprise is that the commercial internet may start moving away from trusting what people see and hear toward verifying cryptographic authenticity.

9. The data-center backlash becomes a genuine political movement

60%

Politics / infrastructure

A substantial number of announced data-center projects are delayed or cancelled because local communities oppose higher electricity bills, water usage and environmental costs.

This is already emerging: voters in at least 38 US jurisdictions approved measures restricting data centers in the November 2026 elections.

The Washington Post+1


My prediction is that 2027 brings a structural change in permitting, cost allocation and the political conditions required to build AI infrastructure.

The surprise: AI infrastructure growth is constrained by local democratic politics rather than technology or capital.

10. Robotaxis become a real urban transportation competitor

40%

Mobility / automation

Robotaxis move beyond novelty and begin capturing meaningful ride-hailing demand in several cities.

By the end of 2027, I expect at least one major city to see autonomous vehicles become a top-three ride-hailing option by usage.

The foundation is already there: commercial services operated in 15 US cities by September 2026, according to McKinsey.

McKinsey & Company


The surprising impact may be on parking, urban transport, vehicle ownership, insurance and the economics of conventional ride-hailing—not simply on automakers.

One source of deflation coming – GTA6!

Grand Theft Auto VI is set to launch on November 19, 2026.

The game content is about 80 hours.

If someone spends 5 hours per day on weekends and 2 hours per day on weekdays that is 20 hours a week, then the game can last 4 weeks.

To play games, you will skip expensive dinners and pubs, going less outside thus spending less on gas or uber.

And the inflation on PS5 is front-loaded!

Gold price pullbacks

Gold has fallen approximately 27% from its January 2026 all-time high ($5,595) to below $4,000 recently ($3,899 on October 30).

To be fair, it rose 65% in 2025 alone. Investors are still sitting on substantial gains if they entered the trade early.

Historically, gold has experienced several major drawdowns of 40–60%.


According to the World Gold Council, gold has experienced five major historical bear runs, each involving a decline greater than 20%.

Period Previous rally Peak-to-trough decline Duration of decline
1974–1976 +353% −43% 21 months
1980–1982 +541% −52% 22 months
1983–1985 +57% −57% 25 months
1987–1999 +71% −48% ~12 years
2011–2015 +612% −42% 52 months

Source: World Gold Council via ChatGPT

US real yields (rising), the dollar (strong) are the two major forces to drive gold price down.

In 2026, US real yields rose from below 2% at the beginning of the year to almost 3% by end of October – that is a 1% increase, but still not that big compared with previous periods of gold declines (1974–1976 and 1980–1982).

The 2011-2015 gold decline – real yield rose small.


China‘s car export more than 6-fold in 5 years

In 2021, China exported 2mn cars, or 7.7% of its total car production of 26mn that year.

The number of exported cars jumped every year, to

3.1mn in 2022 (11.5% of total production),

4.9mn in 2023 (16.3% of total production),

5.9mn in 2024 (18.7% of total production),

7.1mn in 2025 (20.6% of total production).

In 2026, from Jan to Sep, China has exported 35% of its total production, which has already surpassed 8mn.

At the current rate of 1mn per month, the 2026 exports could be 13mn, which is a more than 6-fold jump from 2mn in 2021!

In terms of percentage of production, export ratio is jumping more than 4-fold, from 7.7% to 35.5% currently.

Among the 8mn cars exported this year till Sep, about 50% are new energy vehicles (4mn).

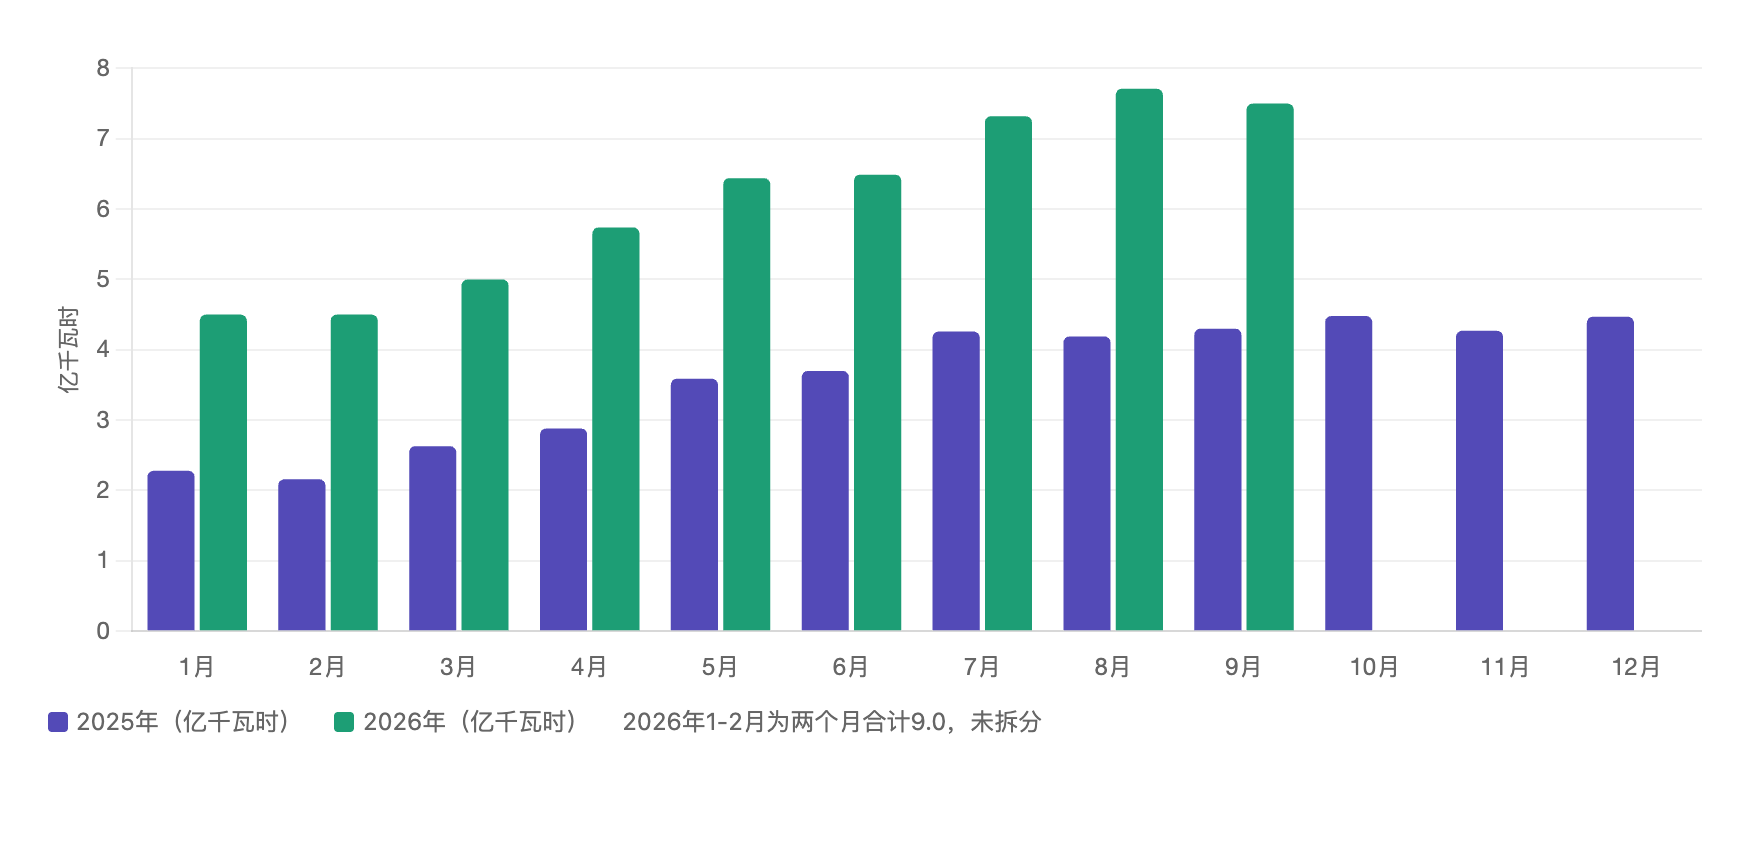
Ulanqab electricity usage (data centers)

Ulanqab has become one of the most important hubs for China (AI) data centers now.

Government official data is a reliable source of its electricity consumption growth.

2026 Jan and Feb are reported together.


Data

Month GWh GW % yoy
2025-01 228 0.31
2025-02 216 0.32
2025-03 263 0.35
2025-04 288 0.4
2025-05 359 0.48
2025-06 370 0.51
2025-07 426 0.57
2025-08 419 0.56
2025-09 430 0.6
2025-10 448 0.6
2025-11 427 0.59
2025-12 447 0.6
2026-01 450 0.63
2026-02 450 0.66 102.8% (together with Jan)
2026-03 500 0.67 90%
2026-04 574 0.8 99%
2026-05 644 0.87 79%
2026-06 649 0.9 75%
2026-07 732 0.98 72%
2026-08 771 1.04 84%
2026-09 750 1.04 74%

Capex peaking

Oracle capex to peak in FY28, or Jun 2027–May 2028.

Following a period of peak capex in FY27-FY28, capital expenditures are expected to step-down in FY29.

– Oracle Investor Day Oct. 28, 2026


MSFT capex missed. Microsoft guided capex for next q is $50bn vs expectation of $53bn, while reported capex for current quarter is $39bn vs expected $46bn.

And MSFT mentioned higher return on capex in future.

we continue to improve the efficiencies of our infrastructure, each dollar of CapEx has the potential to support more revenue and higher returns over time

– Microsoft Fiscal 2027 first quarter earnings call

Sounds to me that capex efficiency is bottoming, which could mean price appreciation in hardware is peaking.


Google stock didn’t do well with higher capex comments in FY2027, although stock is also under pressure with Google ads, which is under threat from AI.

Sovereign debt

Sovereign debt is becoming an topic lately with rising yield and France is under the spotlight.

What is considered “dangerous” in sovereign debt?

Probably not just high debt-to-GDP ratio… because Japan is over 200% on the ratio (highest among G20), but is typically not considered the most dangerous.

Japan debt is mostly in yen and held by domestic investors.

I think also need to consider gov revenue as % of GDP and net debt vs gross debt.

Asked ChatGPT and it give me this.

Given Japan’s investor base and USD’s global status, it looks like Indonesia, South Africa are the most dangerous, while Italy and UK are the most dangerous among developed countries.


General government; latest available 2025 figures, except Japan and South Korea (2024). Ranked highest to lowest.

Rank Country Net debt / GDP Revenue / GDP Net debt / revenue
1 Japan* 141.1% 35.5% 3.98x
2 United States 96.7% 30.5% 3.17x
3 Indonesia 38.5% 13.3% 2.90x
4 South Africa 75.7% 28.5% 2.66x
5 Italy 127.7% 48.1% 2.65x
6 United Kingdom 93.6% 38.2% 2.45x
7 Mexico 53.2% 25.0% 2.13x
8 France 108.4% 52.2% 2.08x
9 Brazil 66.8% 39.5% 1.69x
10 Germany 47.1% 47.2% 1.00x
11 Saudi Arabia 22.6% 23.3% 0.97x
12 Australia 33.9% 36.7% 0.92x
13 Türkiye 18.0% 29.5% 0.61x
14 Canada 10.4% 42.3% 0.25x
15 South Korea* 8.1% 32.0% 0.25x
— China N/A 25.0% N/A
— India N/A 20.9% N/A
— Argentina N/A 31.0% N/A
— Russia N/A 35.3% N/A

Sources: IMF WEO net-debt series and general-government revenue series, via IndexBox and The Economy Pulse. Ratios calculated from rounded inputs. *Japan and South Korea use 2024 data because matched 2025 revenue and net-debt observations were not independently verified. The figures are indicative and underlying publication vintages may differ.